
Blogs
PW Consulting: Global Litz Wire Market to Hit $1.08B by 2032 at 6.85% CAGR, Asia Pacific Leads
By pmarketresearch, 2026-09-16
Unlocking Growth in the Global Litz Wire Market: A Strategic Imperative for 2026 and Beyond
As industries accelerate their transition toward electrification, miniaturization, and high-frequency connectivity, Litz wire has evolved from a niche winding component into a foundational enabler of next-generation power and signal transmission systems. The worldwide market for this specialized conductor, engineered to mitigate skin effect and proximity losses at elevated frequencies, is experiencing a structural inflection point. For executives, procurement leaders, and strategic planners operating in 2026, understanding the underlying trajectories of demand, supply constraints, and competitive realignments is no longer optional. It is a prerequisite for capital allocation, supplier diversification, and product roadmap execution.
Worldwide Copper Litz Wire Market
The macro trajectory underscores this urgency. Between 2020 and 2025, the global market expanded steadily, reflecting consistent industrial uptake and the gradual mainstreaming of high-frequency power architectures. Looking forward, the forecast horizon from 2026 through 2032 projects a compound annual growth rate of 6.85 percent, translating historical momentum into sustained expansion. Revenue measured in millions of USD is anticipated to cross the seven hundred fifty six million threshold in 2026 and continue its upward march toward the one billion mark by the end of the decade, with further acceleration projected into 2032. These figures are not isolated statistics; they represent a measurable shift in how manufacturers, energy infrastructure developers, and medical device engineers approach conductor selection under tightening efficiency mandates and rising performance expectations.
Why These Numbers Matter for 2026 Decision-Making
The forecast period does not merely describe a continuation of past trends. It captures the convergence of multiple structural drivers that will redefine sourcing strategies, regional footprint planning, and technology investment priorities in the coming fiscal year. Automotive electrification and the rapid scaling of battery management architectures are compressing design cycles, forcing OEMs and Tier suppliers to evaluate conductor geometries that balance thermal resilience with high-frequency current handling. Simultaneously, the renewable energy and power supply sector is reengineering transformer and inverter topologies to meet grid stability requirements, creating sustained demand for precision-wound Litz configurations. Even traditionally conservative verticals such as medical instrumentation and industrial automation are prioritizing signal integrity and power density, pulling specialized wire architectures into mainstream engineering specifications.
For 2026 strategy teams, this environment demands more than superficial market sizing. It requires granular visibility into how demand vectors interact with production constraints, regulatory timelines, and raw material volatility. Decision-makers must assess which applications will absorb capacity first, how pricing architectures will adapt to input cost fluctuations, and where regional supply networks are likely to reconfigure in response to trade policy shifts. The strategic value of a comprehensive market intelligence report lies precisely in its ability to convert broad growth narratives into actionable allocation frameworks, risk mitigation pathways, and partnership evaluation criteria.
Navigating a Rapidly Evolving Competitive Landscape
The market concentration profile reveals a moderately consolidated playing field, where the top three participants collectively account for approximately thirty five percent of aggregate revenue, while the top five expand their combined share to nearly forty eight percent. This structure indicates a mature core of established manufacturers that have invested heavily in process engineering, certification portfolios, and application-specific development, alongside a periphery of agile specialists and regional producers capturing niche demand. The competitive dynamics are increasingly defined not by volume alone, but by technical differentiation, compliance readiness, and the ability to synchronize supply with fast-moving engineering programs.
Several cornerstone players illustrate the spectrum of strategic positioning shaping the market. Elektrisola, headquartered in Stolberg, Germany, maintains its stature as a global leader in enameled Litz wire production, with engineering emphasis on high-frequency inductors, transformers, and wireless charging architectures. Its recent introduction of a high-temperature Litz wire series tailored for EV wireless charging coils, certified to IATF 16949 standards, signals how incumbents are aligning product roadmaps with automotive qualification requirements and thermal stress scenarios. Across the Atlantic, MWS Wire Industries in Westlake, Ohio, continues to specialize in custom strand configurations for RF, medical, and aerospace environments. Its showcase of ultra-fine Litz wire for 5G antenna systems at CWIEME Americas highlights the sector-wide push toward miniaturized, high-efficiency signal conductors in telecommunications infrastructure.
North American manufacturing relevance is further reinforced by New England Wire Technologies, based in Lisbon, New Hampshire, which focuses on high-performance Litz wire for motors, sensors, and power electronics with an explicit emphasis on miniaturization. The firm's recent renewal of AS9100D certification for aerospace-grade production demonstrates how quality management frameworks are becoming competitive differentiators in regulated supply chains. Sam Dong Co., Ltd., operating from Gyeonggi-do, South Korea, occupies a strategically positioned role in Asian automotive ecosystems, producing Litz wire for EV chargers, inductors, and high-power applications. Its execution of a multi-year supply agreement with a major EV battery manufacturer underscores the commercial momentum linking conductor supply directly to electrified mobility scaling.
Worldwide Litz Wire Market
Global operations and high-volume production pathways are represented by Essex Furukawa, with its Fort Wayne, Indiana headquarters and worldwide operational footprint, delivering Litz wire variants for magnet wire applications in renewable energy and industrial transformers. In parallel, Ruiyuan Group, headquartered in Dongguan, China, functions as a high-volume producer serving consumer electronics and power supply markets, reflecting the scale advantages that Asian manufacturing ecosystems bring to cost-sensitive, high-throughput segments. On the application-specialist side, Cooner Wire in Chatsworth, California, provides standard and custom configurations for audio, RF, and medical device applications, while Fujikura Ltd., based in Tokyo, Japan, develops advanced Litz wire solutions for telecommunications and high-frequency components. Collectively, these organizations illustrate how competitive advantage is increasingly constructed through application-specific engineering, certification depth, and geographic supply alignment rather than commodity volume alone.
Forces Reshaping Supply, Cost, and Regional Access
The forward strategy calculus cannot be isolated from the operational realities currently pressing on production economics and trade flows. Raw material volatility remains a central consideration, with copper pricing exhibiting notable year-over-year increases as of early 2026, directly pressuring Litz wire manufacturing costs and prompting suppliers to revisit pricing architectures, alloy substitution evaluations, and inventory buffering strategies. The insulation and enamel supply chain introduces a parallel layer of complexity, as extended lead times for polyimide enamel resins reflect ongoing resin shortages that constrain production scheduling and require procurement teams to plan further ahead with qualified alternative material pathways.
Regulatory and compliance shifts add another dimension of strategic urgency. The updated EU RoHS Directive framework, mandating lower halogen content in wire insulations effective in 2026, compels manufacturers and downstream integrators to validate insulation material compatibility, re-qualify supplier portfolios, and adjust formulation specifications ahead of compliance deadlines. At the same time, geopolitical and trade dynamics are recalibrating cross-border material movement. Export controls related to high-purity copper enablers have tightened for China-bound Litz wire components, prompting regional supply chain actors to evaluate sourcing architectures, inventory localization, and second-source qualification strategies. Concurrently, customs enforcement actions imposing substantial tariffs on certain Chinese Litz wire imports have elevated the cost calculus for buyers relying on trans-Pacific procurement, reinforcing the case for regional supplier diversification and localized assembly considerations.
These intersecting forces are not isolated disruptions. They form a compound environment where cost management, regulatory readiness, and geographic access must be modeled together. Firms that continue to treat Litz wire procurement as a transactional purchasing function will face mounting exposure to lead-time variability, compliance friction, and margin compression. Those that embed the market's structural dynamics into supplier evaluation matrices, engineering specification reviews, and regional capacity planning will be better positioned to absorb volatility while preserving performance and schedule integrity.
What This Study Delivers for Strategic Teams
A rigorous market assessment must move beyond headline sizing and concentration ratios to provide the operational scaffolding required for 2026 execution. The research framework is designed to equip decision-makers with a layered view of the market, integrating historical performance baselines, forward forecast horizons, and structural segmentation that clarifies where demand is accumulating and how different product architectures are positioned. The analysis maps the interplay between conductor geometry preferences, application-driven qualification requirements, and regional demand profiles, while maintaining a disciplined focus on the variables that most directly influence sourcing, investment, and partnership strategy.
The study examines competitive positioning by synthesizing company profiles, technological emphasis, production specialization, and recent commercial milestones, enabling readers to benchmark incumbents, assess emerging entrants, and identify capability gaps that may present partnership or acquisition opportunities. It contextualizes market movements within the broader ecosystem of material availability, regulatory timelines, and trade policy evolution, offering a framework for scenario planning around cost behavior, supply continuity, and compliance adaptation. The deliverable structure supports multiple internal use cases, including procurement strategy refinement, R&D specification alignment, regional market entry evaluation, and capital allocation prioritization for high-growth application segments.
Importantly, the research preserves the granularity required for defensible planning without exposing the market to oversimplified narratives. Regional demand distributions, application-level revenue architecture, and product-type market shares are analyzed in depth to reveal the relative weight of each segment, the pacing of adoption across use cases, and the structural implications for manufacturing capacity and supplier service portfolios. This level of detail is essential for teams that need to determine where to concentrate negotiation leverage, which applications warrant accelerated engineering support, and how to sequence supply commitments in a market where timing differentials can translate directly into competitive advantage or exposure.
Positioning for the Next Wave of Electrification and High-Frequency Integration
The Litz wire market in 2026 is defined by a rare alignment of steady structural growth, accelerating application diversification, and a supply environment that rewards preparedness. The combination of a sustained growth trajectory, a moderately consolidated competitive base, and an ecosystem shaped by material constraints, regulatory updates, and trade realignments creates both opportunity and complexity. Organizations that approach this landscape with disciplined market intelligence will be able to prioritize the right applications, qualify the right partners, and build sourcing architectures that can withstand short-term volatility while capturing long-term demand.
The full Worldwide Litz Wire Market research study expands each of these dimensions into a comprehensive, decision-ready intelligence package. It provides the segmented market architecture, regional and application-level analysis, competitive profiling, and scenario-oriented context necessary to translate broad industry momentum into concrete strategic action. For executives preparing capital plans, procurement roadmaps, and technology investment decisions for the 2026 to 2032 horizon, the complete study offers the depth, structure, and current intelligence required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Litz Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Berberine HCl API Market Hits $81.5M in 2025, Projected to Reach $141M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Decision Cycle: Inside the Global Berberine Hydrochloride API Market
The global berberine hydrochloride API market has entered a decisive expansion phase. In 2025, the worldwide market reached an estimated revenue of USD 81.5 million, building on a robust historical trajectory that saw the space grow from USD 55.08 million in 2020. Forecasts for the 2026 to 2032 window project the market to advance to USD 85.86 million in 2026 and further to USD 141.04 million by the close of the forecast period, supported by a compound annual growth rate of 8.15 percent. This growth narrative reflects more than steady volume increases. It signals a structural transition in how manufacturers, formulators, and procurement leaders source, qualify, and deploy berberine hydrochloride across dietary supplements, pharmaceutical formulations, and animal healthcare segments.
Worldwide Berberine Hydrochloride API Market
For executives setting strategy in 2026, these headline figures are only the starting point. The real decision value lies in understanding where growth concentrates, which sourcing pathways carry the least operational and regulatory friction, and how the competitive field is consolidating around vertically integrated supply chains. Our comprehensive Worldwide Berberine Hydrochloride API Market study translates macro momentum into actionable intelligence, giving sourcing directors, R&D leads, and commercial planners the clarity required to navigate pricing volatility, capacity constraints, and evolving pharmacopeial expectations.
This research is designed as a decision-support instrument rather than a static market summary. The analysis covers the full value chain, from botanical feedstock availability through extraction, crystallization, and API purification, to final deployment in regulated and non-regulated end-use channels. By anchoring historical data from 2020 through the base year of 2025 against forward projections through 2032, the report establishes a credible baseline for scenario planning. Readers gain visibility into the demand rhythms that shape quarterly procurement, the regional manufacturing footprint that influences lead times, and the quality infrastructure that determines market access.
A central feature of the study is its operational orientation. Rather than presenting undifferentiated growth statistics, the report decomposes demand and supply drivers into practical dimensions that procurement and production teams can act upon. The analysis examines how botanical inputs such as Coptis chinensis rhizomes, Phellodendron amurense bark, and various Berberis species roots and bark shape cost structures and supply resilience. It also maps the manufacturing clusters that dominate global output, with particular attention to Chinese provinces that benefit from proximity to raw material sources and vertically integrated processing capabilities. This structural perspective helps readers anticipate where capacity is likely to expand, where bottlenecks may emerge, and which sourcing geographies align with their quality, lead-time, and cost targets.
The report also addresses the regulatory and quality environment that governs market participation. Pharmaceutical-grade berberine hydrochloride API must satisfy demanding purity specifications, typically ranging from 98.0 percent to 105 percent by HPLC, alongside strict heavy metal limits and compliance with recognized pharmacopeial standards under GMP conditions. Manufacturers operating in this space increasingly provide DMF documentation, third-party testing for heavy metals and microbial limits, and certification frameworks such as cGMP, ISO 9001, and WHO-GMP. By integrating these requirements into the market assessment, the study clarifies which suppliers are positioned for regulated-market exposure and which production models are best suited to supplement and nutraceutical channels.
Competitive dynamics form another essential pillar of the analysis. The industry is characterized by a moderately concentrated field in which leading players collectively hold a significant share of global capacity, while a broader base of specialized producers competes on purity, extraction capability, and export readiness. The report profiles organizations across India and China that have established berberine hydrochloride API as part of their bulk drug, phytochemical, and herbal extraction portfolios. These include manufacturers operating under ISO 9001:2015, cGMP, and WHO-GMP certified facilities, as well as producers focused on high-purity bulk output with pharmaceutical and nutraceutical applications. The competitive review examines how these firms differentiate through vertically integrated supply from raw plant materials, advanced extraction and crystallization processes, and readiness to serve regulated international markets.
Metformin Hydrochloride Market
The study further evaluates regional dynamics without reducing the market to a shallow geographic tally. Instead, it contextualizes how major production clusters, export flows, and local raw material access influence pricing, availability, and risk exposure for global buyers. This regional lens helps decision-makers understand why certain sourcing hubs command disproportionate share, how logistics and regulatory alignment shape channel strategy, and where diversification may reduce dependency on single-origin supply. Insights into market concentration and the balance between dominant suppliers and niche producers give procurement leaders a clearer picture of negotiation leverage, alternate sourcing options, and long-term supplier viability.
Beyond structural description, the report connects market data to practical planning use cases. For commercial teams, the analysis supports market-entry prioritization by identifying the application channels and geographic corridors with the strongest growth alignment. For supply chain leaders, it informs dual-sourcing strategies, inventory buffering, and qualification pathways for alternative API sources. For R&D and product development groups, the report clarifies purity and documentation thresholds that affect formulation choices and time-to-market in regulated contexts. By bridging historical performance, forward forecasts, and operational requirements, the study equips multiple functions with a shared evidentiary base for 2026 planning.
The strategic relevance of this research is amplified by the pace of change across the berberine hydrochloride API ecosystem. Demand continues to be shaped by expanding supplement adoption, ongoing pharmaceutical interest in gastrointestinal and metabolic indications, and growing animal healthcare applications. At the same time, supply-side realities, including botanical harvest variability, extraction efficiency, and compliance with pharmacopeial expectations, create a market where informed sourcing decisions have direct financial and quality consequences. Executives who rely on aggregate market figures alone risk over-simplifying a landscape defined by feedstock dependence, certification intensity, and geographically uneven capacity. This report is built to close that gap.
Readers who engage with the full study will find a detailed segmentation framework, comprehensive competitor profiling, regional demand and supply balances, and forward-looking scenario analysis calibrated to the 2026 to 2032 horizon. The report connects revenue trajectories to underlying drivers, translating the projected expansion from the 2026 estimate to the 2032 endpoint into a coherent narrative about capacity additions, channel shifts, and competitive realignment. It also addresses the operational realities that determine whether growth is accessible to a given organization, including regulatory documentation, quality system maturity, and the ability to secure consistent botanical feedstocks.
The publication is intended for a broad strategic audience. Procurement and supply chain executives can use the analysis to validate sourcing geography choices, assess supplier qualification pathways, and stress-test procurement plans against capacity and compliance variables. Commercial and business development teams can leverage the market outlook to prioritize product launches, evaluate channel opportunities, and calibrate revenue assumptions for berberine-based offerings. R&D, quality, and regulatory stakeholders can reference the report’s documentation and purity expectations to align development programs with market-access requirements. Investment and corporate strategy teams can use the competitive and regional mapping to understand consolidation patterns and identify where value is likely to accrue over the forecast period.
As the market moves from the 2025 base year into the 2026 decision cycle, the margin between informed and reactive planning will widen. The projected trajectory toward USD 141.04 million by 2032 suggests that berberine hydrochloride API will remain a strategically important ingredient class, but realizing value from that growth requires more than tracking top-line numbers. It demands a clear view of where supply is generated, how quality and compliance expectations vary by channel, which competitors are positioned to scale, and how regional dynamics influence cost and continuity. Our Worldwide Berberine Hydrochloride API Market research is structured to provide precisely that view.
The full report extends well beyond the macro outline presented here. It delivers a granular segmentation analysis, detailed competitor evaluations, regional demand and supply mappings, and forward scenarios that connect volume growth with the operational conditions required to capture it. For organizations preparing sourcing strategies, launch plans, or investment assessments in 2026, the complete dataset and interpretive commentary offer the depth necessary to act with confidence. To access the full market intelligence, including the detailed segmentation splits, competitive profiles, and forward projections that underpin this strategic overview, visit the source page and download the complete research.
For detailed analysis of this topic, please visit the official page: Worldwide Berberine Hydrochloride API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicon Etching Market to Reach $7.6B by 2032, 9.15% CAGR | Asia Pacific Leads
By pmarketresearch, 2026-09-16
Beyond Countrols: Strategic Intelligence for the Worldwide Silicon Parts for Etching Market (2026–2032)
In the high-stakes arena of semiconductor fabrication, the performance of plasma etching equipment is often defined by the consumables it employs. Silicon parts for etching—including focus rings, electrodes, and wafer edge rings—are not merely accessories; they are critical determinants of etch uniformity, process stability, and yield. As the global semiconductor industry accelerates toward advanced logic nodes and high-density memory devices, the demand for high-purity silicon components is experiencing a structural shift. PW Consulting's latest research, Worldwide Silicon Parts for Etching Market, offers a comprehensive strategic lens into this evolving landscape, providing the intelligence necessary for stakeholders to navigate the forecast period of 2026 to 2032.
This report is not simply a collection of figures; it is a decision-support tool designed for executives, investors, and supply chain strategists. By analyzing historical trajectories from 2020 through 2025 and projecting forward, we uncover the underlying drivers shaping the market's expansion. The base year analysis for 2025 establishes a robust foundation, with the market having grown significantly over the past half-decade. This momentum is expected to continue, driven by the relentless scaling of semiconductor manufacturing and the increasing complexity of etching processes required for next-generation devices.
Market Trajectory and Growth Dynamics
The macroeconomic indicators within this research highlight a compelling growth story. The total revenue for silicon parts used in etching processes has demonstrated consistent upward movement, reflecting the broader expansion of the semiconductor equipment market. Starting from a base of approximately 2.25 billion USD in 2020, the market has climbed steadily, reaching an estimated 4.12 billion USD by 2025. This historical performance underscores the critical role these components play in the fabrication ecosystem.
Looking ahead, the forecast period reveals sustained expansion. Projections indicate that the market will surpass the 4.5 billion USD mark in 2026, continuing its ascent toward higher valuations by the end of the decade. The Compound Annual Growth Rate (CAGR) during the forecast period is estimated at 9.15 percent, signaling a healthy, above-average growth trajectory compared to many mature industrial sectors. This growth is not linear; it is punctuated by technology nodes transitions, capacity expansions in key fabrication hubs, and the increasing replacement frequency of consumables in high-throughput plasma etching environments.
It is important to note that growth rates vary across different dimensions of the market. While the overall trend is positive, specific segments exhibit distinct behaviors based on technological adoption rates and regional manufacturing intensities. Our analysis delves into these variations without exposing sensitive granular data, allowing clients to understand the velocity of growth in their specific areas of interest while maintaining the integrity of proprietary forecasts.
Structural Composition: Types and Applications
The market for silicon etching parts is structurally divided by type and application, each presenting unique value propositions and challenges. By type, the market encompasses silicon rings, silicon electrodes, and other silicon parts. Silicon rings, which include focus rings and edge rings, constitute a significant portion of the demand, as they are essential for maintaining plasma distribution and wafer edge protection during etching. Silicon electrodes, serving as the upper or lower electrodes in etch chambers, are equally critical for process uniformity and are subject to stringent quality requirements due to their direct exposure to plasma environments. Other silicon parts, such as shielding rings and adapters, complete the ecosystem, addressing specific equipment configurations and process needs.
In terms of application, the demand is primarily driven by logic and foundry operations as well as memory device manufacturing. Logic and foundry applications require high-precision etching for complex transistor structures, driving the need for components that can withstand aggressive chemistries and high temperatures. Memory devices, including DRAM and NAND flash, also impose heavy demands on silicon parts due to the high aspect ratios and multi-layer stacking processes involved. The interplay between these application segments and the type of components required creates a complex demand matrix that our report unpacks in detail.
A key operational insight highlighted in the research is the consumable nature of these parts. Silicon components used in plasma etching are typically replaced after a defined number of wafer processes to ensure process integrity. This replacement cycle creates a recurring revenue stream for suppliers but also imposes strict requirements on cost-efficiency and supply reliability for manufacturers. Understanding the lifecycle and replacement frequency is vital for forecasting demand accurately, and our report provides the operational context needed to model these consumption patterns.
Regional Landscape and Supply Chain Concentration
Geographically, the market exhibits a pronounced concentration in specific regions, reflecting the global distribution of semiconductor manufacturing capacity. Asia Pacific stands out as a dominant region, hosting major production and consumption clusters for silicon etching parts. This dominance is largely attributable to the concentrated semiconductor manufacturing investments in countries such as South Korea and China. These nations host a significant number of logic, foundry, and memory fabrication facilities, creating a localized demand surge for high-quality silicon components.
North America and Europe also represent substantial markets, driven by their respective equipment manufacturing sectors and specialized fabrication activities. The rest of the world contributes to the overall market size, though at a smaller scale relative to the primary hubs. Our regional analysis explores the nuances of supply and demand within these areas, examining how local manufacturing capabilities, import dependencies, and regional policies influence market dynamics.
Worldwide Silicon Parts for Etching Market
The market structure is characterized by a moderate level of concentration among key players. The competitive landscape is shaped by a mix of established global suppliers and specialized regional manufacturers. Our report assesses the competitive intensity, market share distribution, and strategic positioning of leading firms. This analysis helps stakeholders identify potential partnership opportunities, assess competitive threats, and understand the barriers to entry in this high-purity materials segment.
Competitive Landscape and Key Players
The industry is served by a diverse array of companies, each bringing distinct capabilities to the table. PW Consulting's research profiles several key enterprises that define the competitive arena, analyzing their operational strengths, product portfolios, and strategic orientations.
Silfex Inc., based in Eaton, Ohio, USA, is recognized for providing high-purity custom silicon components for semiconductor etch applications. Their offerings include critical gas distribution parts and wafer edge rings supplied to major semiconductor processing equipment companies. Silfex's focus on customization and high-purity standards positions them as a reliable partner for equipment OEMs and fabs requiring tailored solutions.
Hana Materials Inc., headquartered in Cheonan-si, South Korea, produces silicon electrodes, silicon rings, and related parts for dry etching processes. Their integrated production capabilities, spanning from ingots to finished parts, allow for greater control over quality and supply continuity. Serving global equipment makers, Hana Materials leverages its South Korean base to align closely with regional demand clusters.
Mitsubishi Materials Corporation, based in Japan, supplies high-quality silicon parts for etching applications in semiconductor equipment. Their longstanding materials expertise and global reach contribute to their presence in the market, particularly in applications demanding exceptional reliability and consistency.
CoorsTek, operating from the USA, offers semiconductor-grade silicon components, including focus and edge rings designed for plasma etch chambers. Their products are engineered to improve uniformity and withstand harsh environments, addressing the core performance requirements of advanced etching processes.
In the Asian supply chain, Ningxia Dunyuanjuxin Semiconductor Technology Corporation (DSTC), located in Yinchuan, Ningxia, China, manufactures a range of silicon components for etching, including focus rings, showerheads (upper electrodes), outer rings, exhaust rings, and shielding rings. Their focus on optimizing plasma uniformity and etching precision reflects the increasing technical sophistication of Chinese manufacturers.
Sicreat, also based in China, develops and produces monocrystalline silicon components for integrated circuit plasma etching. Their product line includes focus rings, silicon electrodes, trays, and plates, characterized by low impurity content and large diameters up to 485mm. The emphasis on monocrystalline quality and large-diameter capabilities highlights the industry's push toward higher performance and yield.
Other notable participants include Semicorex, which supplies silicon parts including etching carriers for semiconductor processes, and Worldex Industry & Trading Co., Ltd. in South Korea, which provides silicon parts for etching in the semiconductor industry. Thinkon Semiconductor (Fujian Dynafine) in China manufactures silicon parts for etching applications, while Techno Quartz Inc. and RS Technologies Co., Ltd. in Japan supply silicon components used in semiconductor etching. KC Parts Tech., Ltd. in South Korea also contributes to the production of silicon parts for etching in semiconductor manufacturing.
These companies collectively shape the market through competition, innovation, and supply chain integration. Our report evaluates their relative positions, strategic moves, and the implications of their activities for the broader industry.
Si Precesors for Semiconductor Market
Industry Dynamics: Technical, Regulatory, and Geopolitical Factors
Several critical dynamics influence the market environment for silicon parts in etching. From a technical standpoint, the requirements for high-purity monocrystalline silicon components are stringent. These parts must meet rigorous impurity and defect standards, including zero dislocation defects, often achieved using Magnetic Czochralski (MCZ) growth techniques. The quality of the silicon material directly impacts the performance and lifespan of the etching components, making material science and manufacturing precision key differentiators for suppliers.
The consumable nature of these parts also plays a role in market dynamics. Components such as focus rings and electrodes are typically replaced after approximately 200 wafer processes in plasma etching equipment. This replacement cycle creates a steady demand flow but also necessitates efficient inventory management and supply chain responsiveness from both suppliers and end-users. Factors affecting process duration, such as changes in etching chemistry or device architecture, can alter replacement frequencies and thus influence consumption rates.
Geopolitical factors further complicate the landscape. The concentration of semiconductor manufacturing investments in Asia Pacific, particularly in South Korea and China, creates regional supply-demand imbalances and opportunities. Supply chain resilience, trade policies, and local content requirements can affect the flow of silicon parts across borders. Understanding these geopolitical undercurrents is essential for companies planning global sourcing strategies or market entry.
Strategic Value of the Research Report
PW Consulting's Worldwide Silicon Parts for Etching Market report is designed to deliver actionable intelligence for decision-makers. By synthesizing market size data, growth projections, segmentation insights, and competitive analysis, the report provides a holistic view of the industry's current state and future direction. The detailed segmentation analysis allows clients to pinpoint growth opportunities within specific types, applications, and regions, while the competitive landscape assessment offers context for strategic positioning.
The forecast period from 2026 to 2032 is critical for planning capital expenditures, capacity expansions, and product development initiatives. With a projected CAGR of 9.15 percent, the market presents significant opportunities, but realizing them requires a nuanced understanding of the underlying drivers and constraints. Our research equips stakeholders with the data and analysis needed to make informed decisions, mitigate risks, and capitalize on emerging trends.
Whether you are a silicon component manufacturer seeking to expand your market presence, an equipment OEM evaluating supply chain options, or an investor assessing the semiconductor materials sector, this report offers the depth and breadth of analysis required to navigate the complexities of the worldwide silicon parts for etching market. The insights contained within are derived from rigorous methodologies and a deep understanding of industry dynamics, ensuring that you have a reliable foundation for your strategic planning.
To access the full spectrum of data, detailed segment breakdowns, and comprehensive company profiles, we invite you to explore the complete report. The full intelligence package provides the granular details necessary to translate market insights into concrete business actions, empowering you to stay ahead in a rapidly evolving industry.
For detailed analysis of this topic, please visit the official page: Worldwide Silicon Parts for Etching Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global UV Roller Coater Market Hits $320M in 2025, Projected 4.85% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the UV Roller Coater Machine Market: Strategic Imperatives for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation driven by sustainability mandates, technological convergence, and shifting supply chain dynamics. Within this complex environment, the Worldwide UV Roller Coater Machine Market stands out as a critical nexus where industrial finishing, printing technology, and environmental regulation intersect. For enterprise leaders, capital allocators, and operational strategists, understanding the trajectory of this sector is no longer optional; it is essential for maintaining competitive advantage. Our latest comprehensive study, Worldwide UV Roller Coater Machine Market, provides an authoritative roadmap for navigating the forecast period from 2026 through 2032.
This research is designed specifically to support high-stakes decision-making in 2026. As organizations evaluate capital expenditures, capacity expansions, and technological upgrades, the ability to distinguish between transient market noise and structural growth drivers is paramount. This article serves as an executive preview of the insights contained within the full report, highlighting the strategic value proposition while outlining the depth of analysis available to subscribers. We invite you to explore the detailed intelligence that will inform your next strategic moves.
Market Trajectory and Growth Dynamics
The UV roller coater machine sector has demonstrated robust resilience and expansion over the past half-decade. Historical data indicates a steady climb in market valuation, reflecting increased adoption across multiple industrial verticals. From a base that marked significant milestones in the early 2020s, the market has progressed toward a projected valuation of USD 342.05 million in 2026. This upward trajectory is anticipated to continue, with the market expected to reach USD 445.8 million by the end of the forecast period in 2032.
Such growth is underpinned by a compound annual growth rate (CAGR) of 4.85 percent during the forecast window. This rate reflects a mature yet expanding market environment where efficiency gains and regulatory pressures are converting potential demand into actual capital investment. The data suggests that while the market has navigated various economic cycles, the fundamental drivers for UV curing and roller coating technologies remain intact. Stakeholders analyzing these figures will notice that the growth is not merely linear but is influenced by specific technological shifts and regional industrial outputs that are dissected comprehensively in our full analysis.
It is important to recognize that these aggregate figures mask complex underlying dynamics. The transition from traditional curing methods to UV-based solutions is accelerating, but the pace varies significantly by application type and geographic maturity. Our report unpacks these variations without relying on oversimplified generalizations, providing instead a nuanced view of where investment yields the highest returns.
Report Scope and Operational Content
To support evidence-based strategy, the research deliverable goes far beyond top-line revenue projections. The study is structured to provide actionable intelligence across multiple dimensions of the value chain. Readers will find detailed examinations of product architectures, deployment models, and end-use efficiencies. The content is curated to answer the specific questions that procurement directors, engineering leads, and strategic planners face daily.
Key components of the analysis include a breakdown of machine types, contrasting automatic and semi-automatic configurations to highlight operational trade-offs. Each category is evaluated based on performance metrics, installation complexity, and total cost of ownership considerations. Furthermore, the report investigates application segments, ranging from furniture and woodworking to flooring, packaging, printing, and other specialized industrial uses. Each segment is assessed for its growth potential, technological requirements, and sensitivity to economic fluctuations.
Geographical coverage is another pillar of the research. The study provides a granular view of regional market performance, analyzing how infrastructure maturity, industrial policy, and local manufacturing hubs influence demand. By understanding regional disparities, companies can better tailor their market entry strategies or expansion plans. The full report contains detailed profiles and data tables that allow for comparative analysis across these geopolitical boundaries, ensuring that no strategic blind spots remain.
Competitive Landscape and Key Players
The market structure is characterized by a diverse mix of established multinational corporations and specialized innovators. Concentration metrics indicate a competitive environment where no single entity holds disproportionate power, with the top three firms holding a combined share of approximately 22.4 percent and the top five reaching 34.5 percent. This fragmentation suggests opportunities for niche players and highlights the importance of differentiation through technology or service quality.
Several key companies define the current competitive terrain. American Ultraviolet, headquartered in the United States, offers the AUV-Coat series of UV roller coaters ranging from 16 to 52 inches in width, specifically engineered for digital and offset printing applications. Their strategy emphasizes custom UV coater solutions and a focus on domestically manufactured equipment for print finishing. Similarly, TEC Lighting, also based in the United States, designs and manufactures UV coating machines and curing equipment, specializing in high-performance UV roller coaters and lamps designed to deliver flawless finishes in printing and industrial settings.
In Europe, BÜRKLE from Germany provides roller coating lines with roller coater and UV dryer units for lacquering and printing applications, offering customer-specific line concepts aimed at high-quality surface coating. Koenig & Bauer AG, another German powerhouse, offers UV coating solutions and roller coaters integrated directly with printing presses for graphic arts and industrial applications. Dubois Equipment, located in the United States, manufactures roll coating machines for applying UV, water, and solvent-based coatings on various substrates, with options to adjust coating thickness via doctor roll speed and direction.
The Asian market features prominent players such as PURETE in China, which specializes in automated surface coating equipment including roller coating lines for wood, furniture, and decoration applications as part of full coating production systems. SENLIAN AUTOMATIC COATING MACHINERY CO., LTD., also based in China, produces UV topcoating roller coaters for glass, photovoltaic, and other flat substrates, emphasizing uniform application and high-gloss finishes for uses ranging from packaging to automotive. Additionally, Kisinhom manufactures UV roller coater machines focused on precision roller coating for industrial surface finishing applications. In the packaging and printing sector, Bobst Group from Switzerland supplies UV coating machines including roller coaters as part of their broader printing and packaging equipment portfolio.
Understanding the strategic positioning of these entities is crucial for benchmarking and partnership identification. The full report includes detailed company profiles, product offerings, and strategic moves that define their position in the value chain.
Technological and Regulatory Dynamics Shaping 2026
The 2026 landscape is being reshaped by significant technological and regulatory shifts. A major development signal emerged in February 2026, with expectations surrounding the launch of a 200mW UV-C LED product by ams OSRAM. This launch is poised to support the replacement of traditional mercury lamps in UV curing systems, including roller coaters. This transition is part of a broader trend where UV-LED platforms in curing systems are expanding at a 20.1 percent CAGR. Energy savings and regulatory pressure are accelerating the replacement of mercury lamps in applications like roller coating, driven by the need for more sustainable and efficient operations.
Worldwide UV Roller Coater Machine Market
Regulatory frameworks are also acting as potent catalysts for innovation. The European Union REACH regulatory framework, along with restrictions such as the German Ink Ordinance and Swiss Ordinance, is driving the development of photoinitiator-free UV curing systems for coatings. Manufacturers who fail to adapt to these compliance requirements risk losing access to key markets or facing operational constraints. This regulatory pressure aligns with a macro driver noted in recent sector analysis: the demand for eco-friendly, solvent-free UV-curable coatings with lower energy consumption and reduced emissions supports adoption of UV roller coaters in wood, furniture, and printing sectors.
Furthermore, supply chain economics are influencing cost structures. Rising precious metal prices, raw material costs, and labor expenses are projected to lift UV LED prices by 5 percent quarter-over-quarter in the first quarter of 2026, with the full-year UV LED market size surpassing US$200 million. These input costs must be factored into long-term investment models. On the equipment side, regional manufacturers are responding to specific market needs. For instance, in April 2026, Foshan XMF Machinery Co., Ltd. released information on UV roller coating machines suited for 800mm to 1300mm width medium-sized furniture and decorative boards, indicating a focus on mid-range industrial applications.
Strategic Value for Decision Makers
In an environment defined by volatility and rapid technological change, access to precise, validated data is a strategic asset. This research empowers stakeholders to move beyond speculation. For capital investment committees, the forecast data provides a basis for ROI modeling and capacity planning. For product development teams, the segmentation analysis highlights where performance requirements are tightening and where innovation is most needed. For market expansion strategists, the regional breakdown offers clarity on where infrastructure is maturing and where opportunities for localization exist.
The report also serves as a risk mitigation tool. By understanding the competitive concentration and the specific moves of key players like American Ultraviolet, BÜRKLE, or SENLIAN, organizations can anticipate market shifts and adjust their positioning accordingly. The inclusion of recent developments, such as the UV-C LED launch signals and regulatory updates, ensures that strategies are grounded in the current reality rather than outdated assumptions.
Ultimately, the goal of this study is to provide a clear lens through which to view the future of the UV roller coater machine market. The insights contained within are designed to be integrated directly into strategic planning processes, board presentations, and operational roadmaps.
Conclusion and Next Steps
The Worldwide UV Roller Coater Machine Market is at a pivotal juncture. The convergence of regulatory pressure, technological advancement in UV-LED curing, and sustained demand for high-quality surface finishes creates a compelling growth narrative. However, realizing value in this market requires more than a general understanding of trends; it demands specific, data-backed intelligence.
This preview has outlined the strategic scope and the key dynamics influencing the sector through 2032. To access the complete dataset, including detailed segmentation splits, comprehensive regional analysis, and in-depth competitor profiling, we encourage you to consult the full research publication. The detailed intelligence available therein will provide the granularity required to execute precise strategic maneuvers in 2026 and beyond. We look forward to supporting your organization with the insights necessary to thrive in this evolving industrial landscape.
Roll Coating Machine Market
For detailed analysis of this topic, please visit the official page: Worldwide UV Roller Coater Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aviation Cabin Management Market to Hit $5.8B by 2032, Growing at 6.1% CAGR
By pmarketresearch, 2026-09-16
Executive Briefing: Why the Aviation Cabin Management System Market Demands Strategic Attention in 2026
The aviation cabin is no longer a passive environment. It has evolved into a highly integrated digital ecosystem where passenger experience, operational efficiency, and safety certification intersect. As airlines, business jet operators, and defense contractors navigate an increasingly complex technology landscape, the Aviation Cabin Management System (CMS) market stands at a critical inflection point. Our latest comprehensive market study, covering historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast period, delivers the strategic intelligence required to navigate this transformation with precision.
For executives making capital allocation, procurement, and partnership decisions in 2026, understanding the trajectory of cabin management technology is not optional. It is a competitive necessity. This briefing outlines the structural forces shaping the market, the competitive dynamics at play, and the actionable frameworks embedded in our full report. It is designed to demonstrate the depth of our analysis while underscoring why a complete, data-rich assessment is essential for informed decision-making.
The Macro Landscape: Growth Trajectory and Market Scale
The global cabin management system market has demonstrated steady, compounding expansion over the past half-decade. Drawing on verified historical data from 2020 through 2025, the market has progressed from an estimated 2.85 billion USD in baseline revenue to approximately 3.85 billion USD in the most recent valuation year. This growth reflects sustained investment in cabin modernization, rising passenger expectations for seamless digital experiences, and the ongoing integration of connectivity and entertainment platforms into core cabin architectures.
Aviation Cabin Management System Market
Our forecast model projects continued upward momentum through 2032, with the market expected to reach approximately 5.83 billion USD by the end of the forecast horizon. This trajectory is underpinned by a compound annual growth rate of 6.1 percent, a figure that reflects both organic expansion and the structural shift toward software-defined cabin environments. Importantly, this growth rate is not uniform across all operator categories or platform types. The interplay between hardware refresh cycles, software upgrade pathways, and regional procurement rhythms creates distinct value pockets that require granular analysis to exploit effectively.
For strategic planners, the key takeaway is that the market is large enough to support meaningful investment but dynamic enough to reward those who understand where value concentrates. The full report dissects these patterns across multiple dimensions, providing the quantitative backbone needed to validate procurement strategies, forecast demand, and benchmark competitive positioning. Readers seeking the complete dataset—including detailed revenue projections, regional breakdowns, and type-specific growth coefficients—are encouraged to access the full report page, where the underlying models and scenario analyses are fully available.
Commercial, Private, and Military Applications: Divergent Demand Drivers
The cabin management ecosystem serves three distinct operational verticals, each with its own procurement cadence, technical requirements, and value propositions. Commercial aviation operators prioritize reliability, passenger throughput, and integration with existing in-flight entertainment and connectivity architectures. Business and private aviation clients, by contrast, emphasize customization, luxury interface design, and the ability to future-proof cabins against rapidly evolving consumer device ecosystems. Military and special mission platforms introduce an additional layer of complexity, demanding hardened architectures, secure communications integration, and compliance with mission-critical reliability standards.
These divergent requirements create a market structure where a single vendor rarely dominates across all segments. Instead, competitive advantage emerges from how effectively suppliers align their product roadmaps with the specific rhythms of each vertical. Our report maps these alignment opportunities in detail, examining how retrofit cycles, new aircraft delivery schedules, and aftermarket service contracts shape demand across commercial fleets, VIP airframes, and specialized defense platforms. The analysis reveals where procurement windows open, where integration bottlenecks persist, and where long-term service agreements can stabilize revenue streams amid volatile capital expenditure cycles.
Regional Dynamics and the Fragmentation of Demand
Geographic variation in fleet composition, regulatory environments, and aftermarket infrastructure creates a complex demand map. Mature markets with established fleet renewal programs exhibit different purchase behaviors than emerging regions where aftermarket retrofits and lease-market activity drive initial CMS adoption. The full report provides a comprehensive regional assessment that examines how local manufacturing ecosystems, aviation authority certification pathways, and airline business models influence procurement timing and vendor selection.
Understanding regional nuance is critical for companies evaluating market entry, partnership formation, or capacity expansion. A strategy that works for a narrow-body retrofit program in one geography may not translate to a wide-body new delivery campaign in another. Our analysis disentangles these variables, offering a structured view of where demand is concentrated, where competitive intensity is highest, and where underserved niches present strategic opportunity. The complete regional matrices, including historical share trends and forward-looking allocation scenarios, are detailed in the full report.
Competitive Landscape: Who Is Shaping the Next Generation of Cabin Management
The competitive field in cabin management systems is defined by a blend of incumbent aerospace suppliers, specialized cabin integrators, and technology-forward newcomers. Several key enterprises illustrate the spectrum of strategic approaches currently shaping the market.
Collins Aerospace, operating under RTX, has advanced its Venue cabin management platform with wireless control capabilities through a dedicated cabin command application, alongside 4K smart monitors and an upgraded graphical user interface. The system supports deployment across more than 50 aircraft models, reflecting a strategy centered on broad platform compatibility and continuous interface modernization for business aviation cabins.
Honeywell International has focused its efforts on the Ovation Select cabin management system, which integrates entertainment, control, and communications functions while optimizing for consumer device connectivity. Its positioning emphasizes seamless interoperability with passenger-owned technology, a key differentiator in the business jet segment where personal device integration is a primary purchase driver.
Diehl Aviation has developed the CANSAS platform, a modular digital control architecture designed to manage cabin functions through a networked, service-oriented framework. Its approach highlights the broader industry shift toward smart cabin technologies and the integration of ancillary systems, such as advanced waste management and environmental control, into a unified cabin management layer.
Lufthansa Technik has strengthened its footprint with its nice cabin management and IFE portfolio, including 4K and HD variants tailored for VIP and business jet applications. Recent innovations have introduced hidden touch display architectures integrated directly into cabin surfaces, reflecting a design philosophy that prioritizes minimalism and uninterrupted aesthetic integration.
Astronics Corporation serves the VIP and VVIP segment with its Avenir IFE and CMS offering, leveraging high-bandwidth Ethernet, native 4K video delivery, fiber optic infrastructure, and comprehensive cabin control functionality. Its architecture is engineered to support the demanding bandwidth and reliability requirements of ultra-luxury and government-operated airframes.
Rosen Aviation has pursued an operator-centric design philosophy with its Celestia CMS platform. Built on an IP-based distributed network architecture, the system emphasizes modularity, redundancy, and high customization for luxury cabin environments, allowing operators to configure control logic and interface layout according to specific operational workflows.
DPI Labs offers the SmartLink decentralized cabin management system, which integrates lighting, entertainment, and comfort control across multiple aircraft categories, including VVIP platforms. Its decentralized architecture aims to reduce single points of failure while maintaining unified command across distributed cabin zones.
Aviation Oxygen Systems Market
Jet Aviation has expanded its capabilities through in-house IFX IFE and CMS development, tailoring cabin control systems for refurbishment projects. Its recent activities demonstrate a growing trend among service-oriented integrators to internalize CMS development, thereby capturing more value along the customization and installation chain.
These firms illustrate a market where differentiation is increasingly driven by architecture choices, user interface sophistication, and the ability to integrate with broader cabin ecosystems. The full report provides detailed competitive profiles, product positioning maps, and an assessment of recent product launches and installation milestones that signal shifting strategic priorities. Access to the complete competitive intelligence section is available through the full report page.
Industry Dynamics: Certification, Standardization, and Cost Realities
The cabin management market does not operate in a regulatory vacuum. Safety-critical software and hardware components must satisfy stringent certification requirements, including DO-178C for airborne software and DO-254 for hardware design assurance. For Level A applications, the cost and timeline implications of compliance can be substantial, with certification pathways extending beyond 24 months and incurring expenditures that reach into the millions of USD. These dynamics influence product roadmaps, delay time-to-market for new features, and shape the competitive advantage of established vendors with mature certification infrastructure.
Parallel to certification complexity is the challenge of standardization. The absence of uniform interfaces and data protocols across aircraft models and fleets creates integration friction, particularly when operators seek to modernize legacy cabins or combine CMS platforms with third-party entertainment and connectivity solutions. Retrofit projects must navigate configuration-specific constraints, and typical upgrade expenditures can vary significantly depending on aircraft type, cabin layout, and the scope of subsystem integration. Our report examines how these factors shape procurement decisions, influence vendor selection criteria, and create opportunities for modular, standards-aligned architectures that reduce long-term integration overhead.
For executives, the practical implication is clear: technology superiority alone does not guarantee market success. Certification readiness, integration flexibility, and total cost of ownership over the aircraft lifecycle are equally decisive. The full report quantifies these dynamics where possible and provides qualitative frameworks for evaluating vendor claims against operational realities.
What the Full Report Delivers: Actionable Intelligence for 2026 Decision-Makers
This market study is structured to support concrete strategic actions rather than abstract observation. Inside the full report, readers will find a comprehensive segmentation analysis that disaggregates market size and growth trajectories across type, application, and regional dimensions. The report includes historical time-series data tracing performance from 2020 through 2025, forward-looking forecasts extending through 2032, and scenario-based sensitivity analysis for key demand drivers.
Additional sections provide a detailed competitive landscape assessment, covering product architectures, recent launch activity, installation milestones, and strategic positioning for each major participant. The report also examines market concentration metrics, offering insight into the balance between incumbent dominance and the emergence of specialized challengers. Procurement and aftermarket dynamics are analyzed alongside certification and integration challenges, giving operators and suppliers a shared reference point for evaluating feasibility and risk.
The study is designed for use by strategy teams, procurement directors, product managers, and investment analysts who need to translate market signals into actionable plans. Whether the objective is to benchmark a current platform against emerging alternatives, identify partnership or acquisition targets, or forecast demand for a specific aircraft segment, the full report provides the structured evidence base required to move from hypothesis to decision.
Conclusion: A Market in Motion, and the Need for Precision Intelligence
The aviation cabin management system market is expanding, evolving, and fragmenting simultaneously. Sustained growth through the end of the decade creates opportunity, but the distribution of that opportunity is uneven. Vendors and operators alike must navigate certification complexity, integration constraints, divergent segment requirements, and intensifying competition from both established aerospace suppliers and agile cabin specialists.
In this environment, high-level summaries and aggregate figures are necessary but insufficient. The decisions that determine competitive outcomes in 2026 and beyond require detailed visibility into where value is created, which architectures are gaining traction, how certification and retrofit economics shape procurement timing, and where regional demand patterns diverge from global averages. Our full market research report delivers that depth. It is built to equip decision-makers with the evidence, frameworks, and forward-looking projections needed to act with confidence.
For organizations serious about positioning themselves within the next wave of cabin management innovation, the complete analysis is essential. The full dataset, competitive breakdowns, and strategic recommendations are available through the complete report page, where the full scope of our research can be reviewed in detail.
For detailed analysis of this topic, please visit the official page: Aviation Cabin Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global ESL Market Hits $2.03 Billion in 2025, Projected 21.15% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Electronic Shelf Label Market in 2026 and Beyond
The global retail landscape is undergoing a fundamental transformation, one where physical storefronts are rapidly converging with digital intelligence. At the center of this shift sits the Electronic Shelf Label market, a segment that has evolved from a niche cost-saving tool into a critical infrastructure layer for real-time pricing, inventory synchronization, and customer experience optimization. As retailers navigate margin pressures, labor constraints, and regulatory scrutiny in 2026, the decision to adopt, scale, or defer ESL deployment is no longer a tactical procurement choice. It is a strategic imperative that will define competitive positioning for the remainder of the decade.
Our latest Worldwide Intellect Electronic Shelf Label Market study offers a comprehensive, data-grounded perspective on this accelerating ecosystem. Designed for executive leadership, strategy teams, and investors, the report maps historical momentum, quantifies forward-looking trajectories, and deconstructs the operational, technological, and competitive forces that will dictate market winners. What follows is a strategic preview of the insights embedded in the full analysis, highlighting why deep, disaggregated intelligence is essential for decision-making in 2026.
The Market Arc: From Early Diffusion to Exponential Scale
The Electronic Shelf Label market has crossed a decisive inflection point. Drawing on historical readings from 2020 through the base year of 2025, the sector has demonstrated a sustained upward trajectory that reflects both technological maturation and accelerating retail adoption. The global market, measured in USD millions, expanded from approximately 780.45 million in 2020 to an estimated 2,026.78 million in 2025, signaling that early pilot programs have given way to scaled, network-wide deployments. This expansion is not a temporary surge; the forecast period spanning 2026 through 2032 projects a compounded annual growth rate of 21.15 percent, with implied forward valuations climbing to roughly 2,404.65 million in 2026 and continuing their ascent toward 7,763.72 million by 2032.
Such momentum is underpinned by several structural catalysts. Retailers are prioritizing pricing accuracy and labor reallocation as associate time shifts from manual label changes to higher-value customer engagement and exception management. At the same time, the operational case for ESLs increasingly extends beyond shelf-edge pricing to integrated digital store orchestration, where pricing, promotional cadence, and inventory visibility are synchronized across the store floor. The implication for 2026 decision-makers is clear: the market is entering a phase where scale economics, ecosystem compatibility, and deployment readiness matter as much as the hardware itself. Leadership teams that treat ESLs as isolated point solutions will miss the compounding value created by interconnected retail IoT architectures.
The forecast trajectory also underscores a widening strategic window. Organizations that delay evaluation or treat ESL adoption as a discretionary initiative risk ceding architectural advantages in pricing automation, promotional agility, and operational data capture. Conversely, firms that approach deployment with a long-term interoperability lens can embed ESL infrastructure into broader digital transformation roadmaps, aligning shelf-edge intelligence with supply chain responsiveness and in-store analytics.
Technology Trajectories and Infrastructure Foundations
Behind the headline growth lies a rapidly diversifying technology stack. The current ESL ecosystem is anchored primarily by E-Paper Display technology, which continues to dominate due to its low power consumption, high ambient readability, and long battery life characteristics that make it especially suitable for large-format retail networks. Complementary LCD-based solutions and a category of emerging alternatives address specific use cases where refresh speed, color capability, or specialized form factors are required, particularly in high-value zones or environments demanding enhanced visual alerts and dynamic signage functionality.
Infrastructure considerations are equally critical. The operational viability of enterprise-scale ESL networks depends on low-power wireless protocols capable of supporting thousands to millions of nodes without degrading signal reliability or inflating energy costs. Bluetooth 5.4 with Periodic Advertising with Responses (PAwR) has emerged as a foundational enabler, allowing retailers to build dense, synchronized networks with minimal power overhead. For technology and operations leaders, the relevant strategic question is no longer whether the underlying connectivity exists, but whether the selected ecosystem can scale across store formats, integrate cleanly with existing retail management systems, and adapt as communication standards and edge computing capabilities mature.
Electronic Shelf Label (ESL) Market
Sustainability has also become a meaningful selection criterion. The elimination of paper label waste, combined with reduced reprint cycles and lower manual labor intensity, aligns ESL deployments with corporate ESG targets and operational efficiency mandates. Major European retail partnerships have explicitly framed ESL rollouts in terms of resource reduction and digital modernization, reinforcing the technology's dual role as both an operational tool and a sustainability enabler. Decision-makers evaluating total cost of ownership should therefore incorporate downstream operational savings, waste elimination, and compliance-related efficiencies alongside upfront hardware and integration expenditures.
Competitive Landscape and the 2026 Deployment Race
The competitive field is both global and multidimensional, spanning ESL integrators, display technology providers, wireless semiconductor firms, and cloud-platform operators. Several companies have established strong footholds by pairing hardware reliability with platform depth and large-scale deployment experience. VusionGroup has positioned itself as a global leader through its VUSION Retail IoT Cloud platform, which integrates ESL capabilities with computer vision and indoor positioning to support complex, large-format retail environments. Pricer AB continues to scale its footprint with an established delivery record across dozens of countries and a growing portfolio that includes shelf-edge communication platforms and cloud ecosystems. SoluM, leveraging its affiliation with Samsung, emphasizes real-time pricing, inventory synchronization, and AI-driven execution for retail and warehouse applications, while Hanshow Technology has expanded its digital store solutions across thousands of stores in multiple countries with next-generation ESL suites and cloud-based management.
Worldwide Intellect Electronic Shelf Label Market
Across the broader value chain, hardware specialists, display technology suppliers, and wireless communication developers contribute critical building blocks. E Ink Holdings provides e-paper display modules widely used in ESL deployments, including large-scale retail projects. Silicon Laboratories supplies wireless system-on-chip solutions and Bluetooth technologies that support low-power ESL networks at scale, including PAwR capabilities for dense node coverage. Additional participants such as Displaydata, M2COMM, Opticon Sensors Europe, Teraoka Seiko, Shanghai SUNMI Technology, Zkong Networks, and Altierre Corporation contribute differentiated strengths in display hardware, wireless communication, cloud-based retail management, and BLE-enabled ESL systems tailored to regional and format-specific requirements. This ecosystem breadth is strategically significant because no single hardware component determines outcomes; deployers must evaluate how well each layer interoperates within a unified store operating model.
Recent market activity illustrates how quickly execution momentum is building. In January 2026, Pricer AB commercially launched its Pricer Avenue shelf-edge communication platform at NRF 2026, integrating with its ESL portfolio to advance in-store automation, LED alerts, and high-value zone performance. In February 2026, Hanshow Technology showcased Store Digital Twin solutions at EuroShop 2026 and received a reta awards 2026 recognition for Top Supplier Retail in the Customer Experience category. On the deployment front, SoluM announced a partnership with Waitrose for a nationwide rollout of Newton Pro ESL across UK stores planned for completion in 2026, and VusionGroup advanced its EdgeSense solution through a partnership with a major German drugstore retailer to support ESL communication, location, and connectivity. At the enterprise scale, Walmart announced in March 2026 a chain-wide rollout of digital shelf labels to all US stores by the end of 2026, building on existing locations to improve associate efficiency and pricing consistency.
These developments point to a market that is no longer testing concepts in isolation. Leadership teams should read the competitive landscape as a signal of which deployment models, integration pathways, and platform capabilities are becoming de facto standards in large retail environments. The firms that can demonstrate reliable at-scale execution, clean system integration, and continuous feature evolution will increasingly shape procurement expectations in 2026 and beyond. For buyers, this means vendor evaluation should prioritize long-term roadmaps, interoperability assurances, and reference deployments in comparable retail formats.
Market Dynamics: Regulation, Retailer Rollouts, and Strategic Risk
Growth acceleration does not eliminate complexity. In 2026, the ESL market is being shaped by a parallel set of dynamics that can materially influence deployment timing, format selection, and regional strategy. One notable area of attention involves legislative developments in the United States. Several state bills introduced during the year, including proposals in Georgia, New Jersey, Oklahoma, and Tennessee, have raised restrictions or prohibitions around electronic shelf labels in food retail contexts, citing concerns over algorithmic or dynamic pricing. While these measures remain in motion, they introduce an important dimension of regulatory risk that procurement and policy teams must monitor as part of any rollout plan. The strategic implication is not paralysis but prudent scenario planning: retailers should evaluate pricing governance models, transparency mechanisms, and compliance footprints alongside technical deployment.
On the demand side, retailer commitment continues to intensify. In the United Kingdom, the Co-op partnership with VusionGroup targets a rollout to nearly 2,400 stores by the end of 2026, emphasizing sustainability benefits such as the elimination of paper waste from traditional shelf labels. Other major retailers have announced similarly ambitious programs, including Morrisons, which is planning a rollout of 10.8 million electronic shelf labels across 497 stores beginning early 2026 as part of a broader shift toward real-time pricing and operational efficiency. These large-scale commitments reinforce the market's transition from incremental adoption to program-level transformation, where ESLs become part of an integrated operational playbook rather than a standalone price-tag replacement.
The net effect for 2026 strategy is a balancing act between speed and resilience. Retailers that move aggressively can capture labor savings, pricing accuracy, and promotional responsiveness, but they must also build internal governance to manage regulatory exposure, data integrity, and change management across store networks. Suppliers and partners that help clients navigate this middle ground, through robust documentation, configurable pricing rules, transparent system behavior, and staged rollout support, will be well positioned to convert market momentum into durable commercial relationships.
What the Research Delivers for 2026 Decision-Makers
The Worldwide Intellect Electronic Shelf Label Market report is structured to convert complex market signals into actionable decision support. Beyond the headline trajectory, the study breaks down the market architecture across region, technology, and application dimensions, giving leadership teams the analytical resolution required to identify where growth is concentrated, which technology pathways are gaining traction, and how demand is distributed across retail formats. The report integrates historical performance from 2020 through the 2025 base year with the 2026 to 2032 forecast horizon, enabling readers to assess both recent momentum and the longer strategic runway.
Equally important, the study provides a structured competitive assessment of the companies shaping the ecosystem. By evaluating provider capabilities, deployment scale, platform scope, and recent strategic moves, the analysis helps buyers, investors, and competitors understand relative positioning and likely consolidation pathways. The report also embeds relevant industry dynamics, including wireless protocol foundations, sustainability considerations, retailer rollout programs, and emerging regulatory developments, so that technical and commercial assessments are evaluated within the same operational context.
For organizations planning 2026 investments, the publication is designed to support multiple use cases: market entry and expansion prioritization, vendor selection and benchmarking, deployment sequencing across store formats, and strategic planning for pricing automation and digital store transformation. It provides the framework required to move from broad market awareness to specific, defensible action plans. The full report contains the detailed segmentation values, regional and application-level breakdowns, and company-specific evaluations that executives need to model investment scenarios and align internal stakeholders around a coherent roadmap.
Conclusion: Why Depth Matters in 2026
The Electronic Shelf Label market is entering a phase where strategy, execution, and external dynamics converge. Growth is strong, adoption is accelerating, and the competitive field is actively defining the standards by which large-scale deployments will be judged. Yet the strategic value of market intelligence lies not in surface-level confirmation that the market is expanding, but in understanding the structure beneath the trend: how technology choices cascade into operational outcomes, which deployment models are proving durable, where regulatory pressure may alter timing, and how competitive capabilities are shifting buyer expectations.
For executives responsible for retail transformation, capital allocation, or market positioning, the margin between reactive adoption and deliberate advantage will be determined by the quality of the underlying intelligence. The Worldwide Intellect Electronic Shelf Label Market study is built to provide that depth, giving decision-makers the clarity needed to plan with confidence across the 2026 to 2032 horizon. To access the complete segmentation analysis, competitive evaluations, and forward forecast detail required for enterprise-grade planning, we invite you to review the full report and its accompanying executive materials.
For detailed analysis of this topic, please visit the official page: Worldwide Intellect Electronic Shelf Label Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Ramp Market Hits $528.6M in 2025, Projected 7.25% CAGR to $862.78M by 2032
By pmarketresearch, 2026-09-16
Strategic Access: Navigating the Worldwide Pet Ramp and Stair Market in 2026
The global companion animal care sector continues to exhibit remarkable resilience, driven by deepening emotional bonds between owners and their pets, rising disposable incomes, and a cultural shift toward treating animals as integral family members. Within this broader ecosystem, the Worldwide Pet Ramp and Stair Market has emerged as a critical frontier for product innovation, supply chain optimization, and consumer-focused design. At PW Consulting, we have synthesized years of primary research, macroeconomic trend analysis, and granular competitive mapping into a comprehensive market intelligence release designed explicitly for executive decision-makers operating in 2026 and beyond.
This introduction outlines the strategic architecture of our latest research deliverable. It is deliberately structured to surface high-level market dynamics, competitive fault lines, and material shifts that demand immediate executive attention. For those requiring precise segmentation revenue streams, regional growth trajectories, or end-user penetration breakdowns, our full report provides the complete analytical framework necessary to translate macro trends into targeted commercial action.
Market Sizing and Long-Term Growth Trajectory
Between 2020 and 2025, the global pet access device sector demonstrated sustained expansion, reflecting both post-pandemic lifestyle adjustments and a structural shift toward aging pet populations requiring mobility support. Historical revenue patterns reveal a steady upward arc, with the market scaling from a baseline in the mid-375 million USD range to an estimated valuation approaching the mid-528 million USD range by 2025. This consistent growth trajectory signals a mature yet still expanding category, where demand is no longer solely convenience-driven but increasingly anchored in mobility management, veterinary recommendations, and preventative care practices.
Looking forward, the forecast window extending through 2032 projects a compound annual growth rate of 7.25 percent. By 2026, global revenue is expected to cross the 574 million USD threshold, with subsequent years charting incremental but compounding gains that will ultimately position the market above the 860 million USD mark by the end of the decade. This growth profile underscores a market transitioning from niche accessory status to a standardized companion-care hardware category. For corporate strategists, this implies sustained addressable demand, but also heightened competition for shelf space, digital visibility, and distribution channel loyalty.
Crucially, this expansion is not uniform across all product architectures or consumer demographics. Growth velocity varies significantly across material preferences, end-user mobility needs, and regional purchasing behaviors. Our complete analysis maps these differential growth vectors, allowing stakeholders to prioritize investment regions, align product roadmaps with high-velocity use cases, and avoid capital allocation into slower-moving sub-segments.
Report Scope: Operational Intelligence for 2026 Decision-Making
Market overview research must move beyond aggregate revenue figures to deliver actionable intelligence. The PW Consulting Worldwide Pet Ramp and Stair Market study is engineered to bridge strategic vision with operational execution. The report delivers a multi-dimensional dissection of the category, including:
- Historical performance mapping across multiple forecast horizons, enabling sensitivity analysis around consumer demand cycles, seasonal purchasing patterns, and macroeconomic spillover effects.
- Material composition breakdowns evaluating the commercial viability, cost structures, and consumer preference alignment of plastic, wood, high-density foam, and metal/lightweight frame solutions.
- End-user application mapping that isolates demand drivers across senior dog mobility support, small breed access requirements, feline assistance products, and specialty small animal use cases.
- Regional market intensity profiles that correlate purchasing power, pet ownership density, veterinary infrastructure, and retail channel maturity with category penetration rates.
- Competitive positioning matrices that evaluate brand differentiation strategies, manufacturing footprints, pricing architectures, and innovation cadence across leading domestic and international players.
- Supply-side cost dynamics analysis factoring raw material price movements, logistics constraints, tariff exposure, and manufacturing localization trends.
The deliverable is designed for category managers, product development leaders, supply chain directors, and corporate strategists who require a decision-ready intelligence foundation. Readers seeking the complete dataset, including precise regional revenue allocations, segment-level market shares, and proprietary forecast sensitivities, will find the full report structured for immediate integration into product planning, pricing strategy, and market entry evaluations.
Competitive Landscape: Differentiation, Manufacturing Models, and Strategic Positioning
The competitive environment within the pet ramp and stair category reflects a blend of established American manufacturers, agile North American specialty brands, and globally integrated OEM/ODM suppliers. This dual structure creates distinct strategic pathways for both branded market participants and behind-the-scenes manufacturing partners.
In the branded segment, several companies have carved defensible positions through design specialization, ergonomics-first engineering, and targeted end-user positioning. PetStep International, Inc. has built recognition around portable, lightweight, high-strength composite folding designs that address vehicle, pool, and home access scenarios, with sustained emphasis on non-slip surface engineering and first-to-market form factors. Pet Loader has oriented its product architecture toward heavy-duty ergonomic steps for vehicles including cars, trucks, SUVs, semis, and boats, with explicit focus on stability, reduced ascent angles, and domestic manufacturing for senior or mobility-limited pets. Pet Gear Inc., operating as a division of Vermont Juvenile Furniture, has expanded its footprint through ultra-light free-standing ramps, bi-fold configurations, and combination stairs-and-ramps systems that prioritize portability and multi-environment use. Royal Ramps has concentrated on foam dog ramps and stairs across multiple styles and sizes for bed and couch access, while Doggo Ramps has differentiated through furniture-grade solid hardwood designs with adjustable features for safe furniture access. Pawnotch and Ruff Ramp have both advanced modern pet furniture positioning, with Ruff Ramp emphasizing custom-made ramps featuring safety guard rails for outdoor stair applications. Pet Classics continues to reinforce hardwood ramps, pet stairs, and accessories for indoor and outdoor scenarios, including signature hardwood solutions for beds, sofas, and windows.
On the manufacturing and sourcing side, the landscape includes globally active OEM/ODM entities that supply foldable car ramps, bed steps, aluminum loading ramps, and custom designs to wholesalers and brand operators worldwide. Changzhou Canbo Travel Products Co., Ltd. (CanboPet) and EZLEE represent examples of manufacturers offering scalable production capacity, BSCI/ISO-aligned quality frameworks, and customization pathways that allow international buyers to adapt specifications to regional market requirements.
Recent product and editorial developments reinforce the importance of positioning clarity. In early 2026, The Spruce Pets published an updated best dog stairs guide highlighting Pet Gear stairs and ramp combinations, Aodisman 3-step ramp options, and multiple foam and wooden alternatives as top-rated commercial products. This kind of third-party editorial validation directly influences consumer consideration and can accelerate category migration toward hybrid stairs-and-ramp configurations. Meanwhile, Pet Loader continued to emphasize direct-from-manufacturer sales of heavy-duty ergonomic pet steps for vehicles in mid-2025, reinforcing a narrative around made-in-USA construction, stability advantages, and direct-to-consumer accessibility. For strategists, these developments underscore the growing relevance of product reviews, ergonomic differentiation, and channel strategy in shaping share-of-consideration.
Stairlift Market
The market concentration data further contextualizes competitive dynamics. A relatively fragmented top-tier structure indicates that no single enterprise dominates share to the point of pricing insulation. This environment rewards brands that can combine material reliability, distinctive design, and channel efficiency, while also creating opportunities for consolidation, strategic acquisitions, and private-label expansion across both mature and emerging distribution networks.
Market Dynamics: Material Economics, Trade Policy, and Product Redesign Pressures
Strategic planning in this category requires an accurate reading of upstream cost pressures and regulatory shifts that influence product economics and time-to-market decisions. In late 2025, several material and trade developments began reshaping manufacturing cost structures and sourcing strategies for pet access hardware.
On the raw material front, polyethylene, polypropylene, polystyrene, and polyvinyl chloride prices continued a downward trajectory in December 2025 amid supply and demand imbalances. This decline created relative cost relief for plastic-based ramp and stair producers, though the benefit was not uniformly translated into consumer pricing due to competing cost layers elsewhere in the value chain. At the same time, PET prices rose modestly due to import tariff effects, introducing selective pressure for manufacturers relying on PET-containing components or packaging. These divergent material trends illustrate why segment-level cost modeling is essential: a blanket assumption of input cost relief can obscure specific material exposures that affect margin stability in particular product lines.
Trade policy developments have added another layer of complexity. New U.S. tariffs on imported PET and rPET resin, effective September 2025, contributed to a price increase of approximately 2 to 3 cents per pound for PET in late 2025, with fuller impacts expected in early 2026. In parallel, 25 percent tariffs on steel and aluminum announced or returned in early 2025 increased costs for metal components and packaging relevant to pet product manufacturing. Broader U.S. tariff actions raised costs for imported materials used in pet products, with aluminum packaging seeing significant pressure due to metal tariffs. These dynamics place a premium on sourcing flexibility, domestic manufacturing capacity, and product architecture decisions that reduce exposure to tariff-sensitive inputs.
For product developers and procurement leaders, the implication is clear: design-to-cost strategies must be re-evaluated in context of material-specific tariff exposure, not just average input prices. Products relying heavily on aluminum frames, metal hardware, or PET-based components may require redesign alternatives, supplier diversification, or regional sourcing adjustments to preserve competitiveness through 2026 and beyond. Our full report provides the detailed material-cost mapping needed to pinpoint which product architectures face the greatest exposure and which manufacturing configurations offer the strongest resilience.
Strategic Takeaways for 2026 Planning
The Worldwide Pet Ramp and Stair Market is no longer a peripheral accessory niche. It is a structurally growing hardware category shaped by pet longevity trends, mobility-conscious ownership, channel expansion, and increasingly sophisticated sourcing expectations. Several strategic implications stand out for organizations operating in or entering this space:
- Product differentiation must be anchored in functional outcomes rather than aesthetic novelty alone. Ergonomic load distribution, safe ascent angles, non-slip surface performance, and weight-to-strength ratios are becoming baseline purchase criteria.
- Material selection decisions now carry dual significance: consumer preference alignment and exposure to tariff-sensitive or price-volatile inputs. Flexibility in component sourcing is likely to be a durable competitive advantage.
- Hybrid product architectures combining stairs and ramps are gaining visible traction in editorial validation and consumer consideration, suggesting that modular or dual-function solutions may capture incremental share in specific use cases.
- Competitive positioning will increasingly reward brands that can combine domestic manufacturing credibility, customization capability, and channel-specific product sizing rather than relying on a single universal SKU strategy.
- The relatively fragmented top-tier concentration suggests room for strategic consolidation, targeted private-label expansion, and regional brand-building, particularly where distribution maturity and channel access can be secured efficiently.
For executives requiring complete regional revenue allocations, segment-level market shares, precise end-user demand splits, and proprietary forecasting sensitivities, the full PW Consulting report delivers the analytical resolution needed for pricing strategy, product portfolio optimization, channel planning, and market entry evaluation. The research is structured to support immediate integration into 2026 strategic planning cycles and to serve as a reference baseline for subsequent scenario modeling.
Worldwide Pet Ramp and Stair Market
Accessing the Full Market Intelligence Package
This overview has highlighted the structural growth narrative, competitive architecture, material-economy pressures, and operational planning priorities shaping the global pet ramp and stair category. It is intended to demonstrate the analytical rigor and strategic relevance of our research while preserving the detailed breakdowns that command executive-level purchasing and portfolio decisions.
Organizations ready to move from directional insight to precise, decision-grade intelligence can access the complete Worldwide Pet Ramp and Stair Market report through the PW Consulting research portal. The full release contains comprehensive segmentation data, competitive profiling, material and tariff impact mapping, and forecast sensitivities designed to support product roadmaps, sourcing strategies, and geographic expansion planning throughout the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Ramp and Stair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CMP Equipment Market Hits $3.87B in 2025, Rises to $6.86B by 2032 with 8.5% CAGR
By pmarketresearch, 2026-09-16
Global CMP Equipment Market 2026-2032: Strategic Intelligence for Semiconductor Investments
The chemical mechanical polishing (CMP) equipment sector stands at a pivotal juncture. As the semiconductor industry races to meet the insatiable demand for advanced logic, high-bandwidth memory, and power devices, planarization technology has evolved from a backend processing step to a critical enabler of device performance and yield. PW Consulting's latest Worldwide CMP Equipment Market research offers a comprehensive, data-driven roadmap for navigating this complex landscape through 2032. This article outlines the strategic imperatives, market architecture, and competitive dynamics that corporate leaders must understand to capitalize on the next growth cycle.
A Market Defined by Structural Growth and Technological Inflection Points
Drawing on a robust historical dataset spanning 2020 through 2025 and extending a forward-looking forecast to 2032, our analysis captures a market experiencing sustained expansion. The global CMP equipment market generated revenue of approximately $3,872.66 million in 2025, having grown from $2,420.50 million in 2020. This trajectory reflects not merely cyclical upturns but a fundamental shift in manufacturing requirements driven by node scaling, advanced packaging adoption, and the proliferation of compound semiconductor substrates. Looking ahead, the market is projected to reach $4,165.01 million in 2026 and continues its upward arc, with a compound annual growth rate (CAGR) of 8.5 percent through the 2026-2032 forecast period, ultimately surpassing the $6,800 million threshold by 2032.
Such growth is not uniform across all segments or geographies. The market architecture is shaped by distinct demand drivers: the migration toward 300mm wafer processing for advanced nodes, the resurgence of 200mm capacity for mature and specialty technologies, and the emergence of dedicated tooling for power and optoelectronic materials. Geographic demand remains heavily influenced by the concentration of wafer fabrication capacity, with Asia Pacific accounting for the predominant share of equipment deployment, while North America, Europe, and the rest of the world contribute complementary growth driven by reshoring initiatives, sovereign chip programs, and specialized R&D ecosystems. Understanding how these regional and application-level forces interact is essential for capacity planning, supply chain resilience, and go-to-market strategy.
Inside PW Consulting's Worldwide CMP Equipment Market Report
Our flagship study is engineered to translate macro trends into actionable intelligence. Rather than offering a superficial overview, the report delivers an integrated analytical framework designed for executives, capital allocators, and strategic planners. The following components form the backbone of the research:
- Comprehensive Market Sizing and Forecasting: A granular, bottom-up and top-down reconciliation of historical revenues from 2020 to 2025, extended through scenario-based projections to 2032. The forecast model incorporates equipment unit shipments, average selling price dynamics, and technology migration curves to capture both baseline and upside cases.
- Segment-Level Architectural Analysis: Deep dives into market segmentation by equipment type—including 300mm, 200mm, and other specialized CMP platforms—and by application, covering foundry and logic IC manufacturing, memory devices, and other IC manufacturing segments. Each segment is evaluated for growth drivers, technology readiness, substitution risks, and capacity utilization trends.
- Regional Demand and Deployment Mapping: An assessment of how wafer fab expansion, logic and memory capacity investments, and regional policy incentives shape equipment procurement cycles. The analysis contextualizes supply-demand balances, lead-time dynamics, and localization requirements that influence procurement decisions.
- Competitive Landscape and Strategic Positioning: Detailed profiles of the ten most influential companies shaping the CMP equipment ecosystem. Each profile examines product portfolio strength, technology differentiation, target end-markets, and strategic momentum, enabling a clear view of where incumbents hold advantages and where challengers are carving out niches.
- Technology and Process Evolution: An evaluation of advancements in slurry composition, pad materials, endpoint detection, and AI-driven process control. The report assesses how these innovations impact tool performance, consumable economics, and fab integration complexity, with particular attention to sub-3nm logic and advanced packaging workflows.
- Regulatory and Input-Material Dynamics: A focused examination of how environmental regulations targeting per- and polyfluoroalkyl substances (PFAS) are reshaping pad material development priorities and supplier roadmaps, alongside supply tightness in petro-based polyurethane affecting CMP pad production costs in key regions.
- Strategic Playbooks and Investment Frameworks: Actionable guidance for equipment manufacturers, fab operators, and investors on capacity expansion timing, product roadmap alignment, partnership structures, and risk mitigation in a market characterized by high concentration and rapid technology refresh cycles.
Competitive Landscape: Concentration, Differentiation, and the Battle for Process Excellence
The CMP equipment market is defined by pronounced competitive concentration, a structural feature that carries significant implications for pricing power, innovation velocity, and customer negotiating leverage. Our analysis indicates a high degree of market consolidation, with the top three players commanding an estimated 85.5 percent share and the top five firms collectively representing approximately 92.2 percent of total market revenue. This concentration reflects the capital-intensive nature of tool development, the stringent qualification requirements of leading logic and memory fabs, and the long-term service and consumable relationships that reinforce incumbency.
Within this consolidated framework, competitive differentiation is increasingly driven by process control sophistication, substrate versatility, and the ability to integrate CMP workflows with adjacent process steps. Applied Materials continues to reinforce its leadership position through platforms such as the Reflexion GT and Mirra families, with a strong emphasis on 300mm wafer processing and AI-driven process control tailored for sub-3nm applications. Ebara Corporation maintains a formidable presence in memory fabs, leveraging its FREX-series single-wafer planarization systems and multi-zone pressure control paired with optical endpoint detection to meet the repeatability demands of high-volume memory production. Tokyo Seimitsu (ACCRETECH) pursues a differentiated strategy by integrating CMP systems with dicing and grinding equipment, addressing the precision planarization requirements of advanced packaging and thinned wafer applications.
A parallel competitive dynamic is emerging around compound semiconductors and specialty substrates. Revasum focuses on CMP and grind-polish systems for silicon carbide (SiC) and gallium nitride (GaN) power semiconductor substrates, targeting 150-200mm wafers in electric vehicle and power applications—a segment with distinct process requirements and growing volume trajectories. Entrepix, operating under Amtech Systems, provides a broad CMP technology portfolio encompassing equipment, consumables, service, and a notable emphasis on refurbished systems and SiC wafer processing, creating a compelling value proposition for cost-sensitive deployments. Axus Technology supplies advanced CMP process development, production foundry services, and equipment solutions, bridging the gap between process refinement and production-scale deployment.
The market also includes specialized players addressing precision lapping, R&D, and optical and compound semiconductor applications. Lapmaster Wolters and Logitech focus on ultra-high surface quality requirements for compound semiconductors, optics, and research environments, where surface finish and minimal defectivity are paramount. Okamoto Machine Tool Works contributes precision grinding and CMP equipment for wafer planarization, while Alpsitec provides specialized CMP solutions for semiconductor manufacturing. The breadth of these profiles underscores that "CMP equipment" is not a monolithic category but a set of application-specific tool families, each with its own technology roadmaps, qualification cycles, and customer engagement models.
Industry Dynamics: Materials, Regulation, and the Acceleration of Demand
Beyond the competitive arena, several intersecting forces are reshaping the CMP equipment value chain. On the materials side, supply tightness in petro-based polyurethane is influencing CMP pad production costs and availability, particularly in North America and Europe. This constraint is prompting manufacturer scrutiny of pad sourcing strategies, inventory buffers, and alternative material pathways. Simultaneously, environmental regulations restricting per- and polyfluoroalkyl substances (PFAS) are actively reshaping CMP pad material development priorities, compelling suppliers to accelerate the qualification of compliant materials without compromising polishing performance or pad life. These dual pressures are elevating the strategic importance of consumable ecosystems and the tool-consumable co-optimization that leading fabs increasingly demand.
On the demand side, the expansion of semiconductor fabrication facilities and the scaling of advanced logic and memory production are primary engines of CMP equipment and consumables demand. The proliferation of new fab capacity, coupled with technology transitions that require more planarization steps per wafer, is strengthening the long-term demand outlook. This trend is reinforced by the growing relevance of hybrid bonding and advanced packaging, where CMP slurry and tools play an enabling role in achieving the surface quality and alignment precision necessary for high-performance interconnects. Recent developments illustrate this momentum: in September 2025, Fujifilm Corporation launched advanced packaging CMP slurry optimized for hybrid bonding technology to support AI semiconductor performance, signaling the intersection of materials innovation and packaging roadmaps. In July 2025, Clarkson University's CAMP and NCCAVS hosted the 27th International Symposium on Chemical-Mechanical Planarization, spotlighting leading-edge CMP technologies and process innovations. In October 2025, SEMICON West 2025 in Phoenix featured CMP-related technologies and awards, underscoring growth in U.S. semiconductor manufacturing and the expanding role of post-CMP applications.
These developments are not isolated events; they are indicators of a structural shift in which CMP is increasingly central to the performance equation across logic, memory, and power device roadmaps. For equipment suppliers, the implication is clear: process adaptability, consumable integration, and service responsiveness are becoming as critical as raw tool capability. For fab operators, the challenge lies in balancing technology migration timelines with consumable cost management and qualification risk.
Worldwide CMP Equipment Market
Strategic Implications for 2026 Decision-Making
As organizations finalize their 2026 capital allocation and product strategy, several themes emerge from our analysis as particularly actionable:
- Align capacity planning with segment-specific demand curves. The divergence between 300mm advanced-node demand and the sustained relevance of 200mm and specialty CMP for power, optoelectronic, and mature-node applications requires differentiated investment theses. Over-indexing on a single substrate or application can expose a portfolio to cyclical or substitution risk.
- Treat consumables and process control as strategic assets, not overhead. In a market where pad and slurry dynamics are influenced by material constraints and regulatory shifts, co-developing tool-consumable-process solutions can create defensible differentiation and stabilize total cost of ownership for customers.
- Monitor concentration dynamics when assessing partnership and procurement options. High market concentration among leading vendors can translate into reliable technology roadmaps but also into negotiating complexity and dependency risk. A balanced sourcing strategy—combining primary platform relationships with specialized or refurb capability where appropriate—can enhance resilience.
- Integrate regional policy and fab expansion signals into scenario planning. With Asia Pacific driving the majority of equipment deployment and North America and Europe expanding capacity under sovereign and reshoring incentives, regional lead-time, localization, and service-network considerations will increasingly influence procurement timing and vendor selection.
- Anticipate technology refresh cycles tied to AI, advanced packaging, and power semiconductor growth. The trajectory toward sub-3nm logic, hybrid bonding, and SiC/GaN power applications will intensify requirements for precision planarization, endpoint detection, and process repeatability. Equipment roadmaps should be evaluated against these end-market inflection points rather than historical baseline volumes alone.
Conclusion: From Macro Signals to Micro Decisions
The Worldwide CMP Equipment Market research from PW Consulting is designed to bridge the gap between high-level market signals and the micro-level decisions that determine competitive advantage in 2026 and beyond. The data tell a clear story of sustained growth, technological differentiation, and a concentrated but increasingly segmented competitive landscape. Yet the most valuable insights lie beneath the headline figures—in the interaction between material constraints and process innovation, in the way regional fab expansion reshapes procurement cycles, and in the strategic choices that determine whether a company leads, follows, or risks obsolescence as planarization requirements intensify across logic, memory, and power device roadmaps.
This article has provided a strategic preview of the market architecture, competitive dynamics, and industry forces that will shape decision-making in the coming years. The full report extends far beyond this overview, delivering detailed segmentation analysis, company-by-company strategic assessments, regional and application-level demand breakdowns, and scenario-based forecasts calibrated to different technology adoption and fab expansion trajectories. For executives seeking to translate market intelligence into concrete investment and operational decisions, the complete research offers the granular, actionable detail required to act with confidence.
CMP Polishing Pads Market
To access the full Worldwide CMP Equipment Market report, including complete segmentation data, competitive profiles, and forward-looking scenarios through 2032, please visit our research portal and secure your copy of this essential strategic resource.
For detailed analysis of this topic, please visit the official page: Worldwide CMP Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rod Gauge Market Hits $461 Million in 2025, Projects 5.12% CAGR to 2032
By pmarketresearch, 2026-09-16
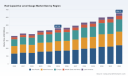
Strategic Intelligence for 2026: Inside the Worldwide Rod Capacitive Level Gauge Market
As industrial operations worldwide navigate a period of accelerated modernization, precise level measurement has emerged as a critical enabler of operational efficiency, safety compliance, and process automation. PW Consulting is proud to introduce our latest comprehensive market intelligence piece—the Worldwide Rod Capacitive Level Gauge Market study. Designed specifically to inform enterprise strategy in the 2026 fiscal cycle and beyond, this report provides a rigorous, data-driven examination of a specialized yet indispensable industrial instrumentation sector. Executives, product planners, and competitive strategists will find actionable insights calibrated to support capital allocation, market entry evaluation, and long-term portfolio positioning.
The global market for rod capacitive level gauges has demonstrated steady, resilient expansion over the past half-decade. Drawing from verified historical records spanning 2020 through 2025, our analysis traces a clear trajectory of commercial maturation. Starting from a foundational valuation of approximately 361.4 million USD in 2020, the industry climbed to 392.9 million USD in 2021 before experiencing a brief technical correction in 2022. Recovery proved swift and sustained, with revenues reaching 428.68 million USD in 2023, 435.14 million USD in 2024, and stabilizing at 461.24 million USD in 2025. These historical baselines anchor our forward-looking framework, which projects a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast window. Under this growth trajectory, market valuation will exceed 466.94 million USD by 2026, advance toward 494.27 million USD in 2027, and continue its upward momentum through 2032, ultimately approaching 654.21 million USD.
Why 2026 Demands a Refined Strategic Lens
The year 2026 represents a decisive inflection point for industrial instrumentation stakeholders. Supply chain realignments, evolving environmental regulations, and the widespread integration of digital monitoring architectures are reshaping procurement behaviors across heavy process industries. Organizations that rely on legacy level-sensing methodologies face mounting exposure to measurement drift, maintenance overhead, and compliance vulnerabilities. Conversely, enterprises that align their instrumentation portfolios with next-generation capacitive rod technologies stand to capture measurable gains in uptime reliability, chemical compatibility assurance, and automated process control. Our study isolates the precise commercial vectors that will dictate competitive advantage during this transition period. Rather than offering generalized industry commentary, we deliver a quantified strategic map that connects technological specification capabilities to actual market demand patterns, pricing elasticity, and regional deployment cycles.
What the Study Delivers: A Practitioner’s Roadmap
This market research publication is structured to translate macroeconomic indicators into operational decision frameworks. Each chapter is engineered to address a specific strategic planning requirement. The analytical architecture includes:
- A complete historical reconstruction of market valuation from 2020 through the current baseline year, paired with a forward projection extending through the end of the decade, enabling accurate budgeting cycles and multi-year capacity planning.
- Application-specific demand profiling across core verticals, including water and wastewater management, chemicals and petrochemicals, food and beverage production, oil and gas operations, and pharmaceutical manufacturing, with emphasis on the distinct measurement challenges each sector presents.
- Product-type segmentation contrasting insulated rod gauge architectures against non-insulated variants, highlighting material compatibility considerations, environmental resilience thresholds, and total cost-of-ownership implications across corrosive, high-temperature, and hygienic process environments.
- Geographic market distribution analysis that maps revenue density, growth velocity, and infrastructure investment pacing across major industrial regions, helping organizations prioritize export logistics, localized service networks, and regional certification pathways.
- Cross-industry contextual intelligence that situates level gauge procurement within broader capital expenditure trends, notably the ongoing scrutiny of facility budgets and the parallel push toward sensor-enabled process optimization that is reshaping how industrial operators justify instrumentation investments.
- Competitive benchmarking that evaluates product roadmaps, portfolio breadth, and market positioning across established manufacturers and emerging challengers, providing a clear view of where differentiation is still achievable.
Competitive Dynamics: Measuring the Incumbents and Challengers
The rod capacitive level gauge landscape is characterized by a moderate concentration of established multinational players alongside a network of highly specialized engineering firms. Our analysis indicates that the top three competitors collectively command approximately 38.45 percent of total market revenue, while the top five players extend their combined share to roughly 54.12 percent. This structure suggests a market that remains accessible to agile entrants while rewarding incumbents who can scale certified product lines across multiple process sectors.
Worldwide Capacitive Height Controller Market
VEGA Grieshaber KG, headquartered in Schiltach, Germany, continues to anchor its commercial strategy on the VEGACAL series of rod probes. Their portfolio spans partially and fully insulated configurations utilizing PTFE, PE, and FEP materials, alongside ceramic-insulated variants, delivering continuous capacitive level measurement for both liquids and bulk solids. Endress+Hauser, based in Reinach, Switzerland, advances a complementary approach through its Liquicap FMI51 and FMI52 rod probes, engineered for continuous level and interface measurement in viscous, aggressive, and deposit-forming media, alongside FTI51 and FTI52 models dedicated to point level detection. Siemens AG, operating from Munich, Germany, positions the SITRANS LC300 capacitance level transmitter with active-shield technology as a continuous measurement solution for liquids, solids, and slurries, while the Pointek CLS200 rigid rod variant addresses point level detection requirements.
Mid-tier and regional specialists add substantial portfolio diversity. KOBOLD Instruments, with its operational base in Hofheim, Germany and United States presence in Pittsburgh, Pennsylvania, manufactures NMC capacitive level transmitters using rod probes ranging from 11 to 157 inches, specifically calibrated for aggressive chemical, pharmaceutical, and food-grade liquids. Dwyer Instruments and Omega Engineering, operating out of Michigan City, Indiana, deliver the LV3000 and LV4000 series capacitive rod probes designed for continuous measurement of liquids, pastes, and solids, with standard 4-20 mA output configurations suited to oils, solvents, and process water applications. NIVELCO Process Control Co., headquartered in Budapest, Hungary, supplies NIVOCAP capacitive level transmitters with rod and cable probe configurations, supporting conductive and non-conductive liquids with standard rod lengths reaching approximately three meters and high-temperature variants, all integrated with 4-20 mA and HART communication protocols.
The competitive field further extends with SenTec from Chengdu, China, whose SRC400 coaxial rod capacitive level gauge targets continuous measurement applications, and BinMaster, based in Lincoln, Nebraska, which specializes in custom-configured capacitance probes for level detection across bins, silos, tanks, and hoppers. European sensor specialists UWT GmbH and Baumer contribute Capanivo and RFnivo series capacitive sensors, including rod-based point level detection designs for demanding liquid and solid environments, while Balluff from Neuhausen, Germany rounds out the competitive matrix with a broad capacitive sensor lineup addressing diverse level measurement tasks.
Recent commercial activity reinforces the strategic relevance of this sector. In January 2026, NIVELCO Process Control Co. released its updated North America product catalog, featuring revised NIVOCAP capacitive level transmitters with rod probes, newly introduced PiloTREK radar models, and a clear emphasis on high-sensitivity capacitive solutions for liquid applications. Such catalog expansions signal an ongoing industry-wide push toward enhanced measurement sensitivity, broader material compatibility, and tighter integration with industrial communication standards.
Market Dynamics and the Case for Strategic Foresight
The rod capacitive level gauge market does not operate in isolation. It responds directly to macro-level capital allocation patterns, regulatory pressure on process transparency, and the accelerating digitization of industrial sensor networks. Across heavy process industries, procurement teams are increasingly weighing instrumentation purchases against broader facility budget constraints and long-term operational efficiency targets. The same financial discipline that shapes hospital and healthcare capital expenditure planning—where executive surveys indicate a cautious outlook on near-term budget expansion—mirrors a wider industrial tendency to prioritize instrumentation that demonstrably reduces maintenance frequency, minimizes process downtime, and supports automated control architectures.
Simultaneously, the steady escalation of operating costs across process-heavy sectors is reinforcing demand for measurement equipment that lowers total cost of ownership through extended service intervals, improved chemical resistance, and reliable performance in challenging media conditions. Level measurement technologies that can deliver continuous, stable readings in corrosive, viscous, or build-up-prone environments are increasingly evaluated not as commodity purchases but as strategic assets within facility modernization programs. Our study maps these behavioral shifts directly to purchasing criteria, helping leaders differentiate between tactical replacements and long-term capability investments.
Worldwide Rod Capacitive Level Gauge Market
How to Use This Research for Your 2026 Decisions
PW Consulting designed this market study to function as an internal reference asset rather than a passive industry overview. Product managers can leverage the type and application breakdowns to align engineering roadmaps with verified demand concentrations. Regional directors can use the geographic revenue distribution to calibrate distribution partnerships, service coverage expansion, and localized certification strategies. Competitive intelligence teams will find direct value in the incument profiling, which clarifies where portfolio overlaps exist and where whitespace opportunities remain viable. Finance and strategy groups can anchor long-range revenue forecasting and scenario modeling to the documented historical series and the 5.12 percent forward growth trajectory.
The full report contains extensive quantitative matrices, vendor capability comparisons, application-specific deployment considerations, and forward scenario analysis that extend well beyond the preview provided here. We have intentionally reserved the complete dataset, granular segmentation matrices, and proprietary competitive scoring methodologies for the full publication, ensuring that subscribers receive actionable intelligence rather than generalized market commentary.
Access the Complete Intelligence Package
The Worldwide Rod Capacitive Level Gauge Market study represents a comprehensive resource for stakeholders who require precise, forward-looking market visibility in 2026 and beyond. By integrating verified historical baselines, disciplined forecast modeling, application-specific deployment insights, and detailed competitive profiling, this publication equips decision-makers with the evidence needed to navigate an evolving industrial instrumentation landscape. Organizations that secure the full report will gain immediate access to the quantitative depth and strategic context necessary to optimize product positioning, inform capital deployment, and anticipate demand shifts across the forecast horizon. We invite executives, strategy leads, and market planners to access the complete research package through our official publication portal and integrate these findings into their 2026 strategic planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Rod Capacitive Level Gauge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Furniture Installation & Relocation Market to Hit $2.4B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Worldwide Furniture Installation and Relocation Service Market (2026–2032)
The global furniture installation and relocation service market stands at a critical inflection point as organizations navigate post-pandemic operational realignments, hybrid work mandates, and escalating logistics complexity. PW Consulting’s latest Worldwide Furniture Installation and Relocation Service Market research delivers a comprehensive, data-grounded assessment of this evolving landscape, providing executives, investors, and service operators with the analytical clarity required to make disciplined strategic decisions throughout the forecast horizon. Drawing on rigorous modeling, primary industry validation, and cross-sector demand mapping, this publication is engineered not as a static snapshot but as a forward-looking decision-support instrument for 2026 planning cycles and beyond.
Market Trajectory and Foundational Intelligence
Historical performance across the 2020–2025 observation window demonstrates consistent revenue expansion, culminating in a baseline valuation of 1,650 million USD in the base year of 2025. Macroeconomic stabilization, sustained commercial real estate repositioning, and the continued normalization of corporate relocation programs have collectively reinforced demand resilience. Forward-looking projections spanning 2026 through 2032 indicate a sustained expansion trajectory, anchored by a compound annual growth rate of 5.45 percent. By the terminal forecast year, the market is positioned to cross the 2,400 million USD threshold, reflecting both organic volume growth and structural shifts in how organizations procure, manage, and redeploy physical assets.
These headline figures, while instructive at a macro level, represent only the outermost layer of a deeply segmented operating environment. Growth vectors vary materially across service typologies, end-user verticals, and geographic footprints, each carrying distinct margin profiles, capacity constraints, and competitive intensity. A disciplined approach requires unpacking the underlying demand architecture rather than relying on aggregated revenue totals. PW Consulting’s methodology isolates these dimensions through granular segmentation modeling, scenario testing, and sensitivity analysis, enabling leadership teams to calibrate capacity planning, pricing strategies, and geographic prioritization with precision.
The service ecosystem itself is undergoing measurable recalibration. Installation-driven engagements continue to anchor a substantial share of total contract value, driven by corporate fit-out cycles, retail refresh programs, and healthcare facility expansions. Relocation services maintain strong momentum as organizations execute footprint optimization and employees navigate hybrid living arrangements. Concurrently, asset management and decommissioning workflows are gaining strategic relevance as enterprises prioritize sustainable asset recovery, lifecycle tracking, and compliance-driven disposal protocols. Each segment operates under different operational economics, labor intensity profiles, and client procurement behaviors, necessitating differentiated go-to-market postures.
Structural Shifts Defining the Competitive Landscape
The market remains moderately fragmented, with no single entity exerting decisive pricing or capacity control. Aggregate concentration metrics indicate that the top three operators collectively account for approximately 18.5 percent of total revenue, while the top five expand that share to roughly 24.2 percent. This dispersion signals ample room for targeted scaling, regional consolidation, and service differentiation, but it also underscores the importance of defensible operational advantages. Companies that thrive in this environment typically combine reliable execution quality, transparent pricing frameworks, scalable dispatch infrastructure, and strong client retention mechanics.
A defining feature of the current landscape is the prominent role of platform-enabled and tech-forward service models. TaskRabbit, headquartered in San Francisco, operates a distributed marketplace architecture that connects end users with localized Taskers for furniture assembly, installation, and relocation across select international markets. Handy, based in New York, delivers an on-demand service platform emphasizing professional installation, assembly, and moving capabilities across major metropolitan corridors in the United States, the United Kingdom, and Canada. Thumbtack, also anchored in San Francisco, functions as a curated marketplace for local professionals specializing in furniture installation, disassembly, and relocation, with a strong domestic footprint. Angi, originally recognized as Angie’s List and now operating from Denver, maintains an online directory and booking infrastructure that routes clients to vetted contractors for installation and relocation work throughout the United States.
Beyond the platform layer, traditional and hybrid operators continue to shape market dynamics through scale, brand recognition, and operational specialization. CORT Furniture Rental & Delivery, headquartered in Chantilly, integrates delivery, installation, and relocation into a broader rental ecosystem, serving corporate and transitional housing demand across the United States and select international locations. Two Men and a Truck, based in Atlanta, operates a nationally distributed moving franchise model with more than 400 locations and international extensions, offering dedicated furniture relocation, disassembly, and reassembly capabilities. Bellhop, operating from Nashville, leverages a tech-enabled moving framework to deliver installation and relocation services across more than thirty-five U.S. cities. Collectively, these organizations illustrate the spectrum of business models competing for share—from marketplace aggregation to branded franchise networks to rental-integrated service bundles.
Operational Economics, Regulation, and Labor Dynamics
Strategic planning in this sector requires direct engagement with structural cost and compliance realities. Labor economics remain a central driver of unit economics. Hourly wages for furniture installers and movers averaged 18.50 USD in the United States as of 2024, according to federal labor statistics, establishing a baseline cost structure that directly influences margin thresholds, pricing elasticity, and service-tier design. At the same time, employment projections for furniture movers anticipate growth of approximately 5 percent between 2023 and 2033, a pace that trails broader occupational averages due to automation exposure and efficiency gains in scheduling, routing, and inventory handling. These dual pressures—rising wage floors and measured employment growth— compel operators to pursue labor productivity improvements, standardized process design, and selective technology adoption rather than relying solely on headcount expansion.
Regulatory and safety frameworks further condition operational execution. OSHA standard 1910.176 mandates safe handling and storage of materials, including furniture, to prevent workplace injuries during installation and relocation activities. Compliance with this standard influences training requirements, equipment provisioning, site assessment protocols, and liability management. In parallel, jurisdictional labor classification rules continue to shape platform economics. California’s AB5 framework classifies many gig workers as employees, altering contractor engagement models for marketplace-based service providers and influencing cost structures, scheduling flexibility, and scalability across affected regions. These regulatory dynamics are not static footnotes; they are active variables that inform market entry timing, operating model design, and risk allocation strategies.
Taken together, labor cost trends and regulatory requirements create a narrow window between service affordability and operational profitability. Operators that institutionalize safety-forward workflows, invest in modular training pipelines, and align workforce models with local compliance regimes are better positioned to sustain margins while preserving service quality. For corporate buyers, these same factors elevate the importance of vendor due diligence, ensuring that installation and relocation partners can demonstrate consistent adherence to safety expectations and labor standards across multiple sites and jurisdictions.
Demand Architecture Across End-User Verticals
The market’s expansion is not uniform; it is anchored by distinct demand profiles that differ in contract size, procurement cycles, service complexity, and retention behavior. Corporate offices represent a dominant share of total demand, reflecting ongoing workspace reconfiguration, hybrid seating models, and periodic relocation of regional hubs. These engagements tend to prioritize scheduling reliability, minimal operational disruption, and coordinated multi-site execution, making vendor capability and account management critical differentiators.
Retail and hospitality demand forms another substantial pillar, driven by seasonal remodels, flagship refreshes, franchise rollouts, and experiential space redesigns. Service requirements in these verticals frequently emphasize speed, aesthetic precision, and clear post-installation handoff procedures. Healthcare and education segments contribute steady, project-based volume characterized by strict compliance expectations, specialized handling requirements, and coordination with facilities management teams. Residential demand, while smaller in aggregate contract value relative to commercial segments, remains a consistent source of recurring activity, often mediated through platform marketplaces, localized service networks, and hybrid rental-and-relocation offerings.
Each vertical carries its own procurement rhythm and performance expectations. Corporate buyers typically evaluate vendors on execution consistency, safety records, and scalable deployment capacity. Retail and hospitality operators weigh speed, site sensitivity, and brand-aligned presentation. Institutional buyers in healthcare and education prioritize regulatory alignment, documented handling procedures, and coordinated logistics. Residential customers, particularly in platform-mediated transactions, emphasize convenience, transparent pricing, and localized availability. Understanding these divergent requirements is essential for service providers seeking to align sales messaging, operational design, and pricing architecture with the segments most compatible with their capabilities.
What the Full Research Delivers
PW Consulting’s Worldwide Furniture Installation and Relocation Service Market report is structured to translate high-level market intelligence into executable planning inputs. The full publication extends well beyond top-line sizing and trend commentary, offering a layered analytical framework designed for use for corporate strategy, venture and private equity evaluation, capacity planning, and competitive positioning exercises.
Worldwide Furniture Installation and Relocation Service Market
Core components of the research include a detailed segmentation architecture that maps service types, end-user verticals, and regional demand structures without reducing them to isolated percentages, preserving instead the relational context needed for strategic interpretation. The forecast model spans 2026 through 2032 and is supported by scenario analysis that accounts for shifts in commercial real estate utilization, relocation program frequency, labor availability, and regulatory evolution. Competitive profiling examines operating models, geographic reach, service scope, and positioning tactics across leading platform, brokerage, franchise, and rental-integrated participants, providing a reference map for benchmarking and differentiation planning.
The report also integrates operational and regulatory context into the market narrative, ensuring that executives can assess how wage structures, safety mandates, labor classification rules, and automation exposure influence margin potential and scalability. Demand-side analysis connects vertical-specific procurement behaviors to service design implications, clarifying where execution reliability, speed, compliance documentation, or localized availability creates the strongest competitive advantage. Additionally, the research surfaces practical guidance on pricing frameworks, capacity allocation, vendor selection criteria, and risk mitigation practices that can be applied directly to 2026 planning cycles.
For organizations evaluating market entry, geographic expansion, or portfolio adjustment, the publication provides a disciplined basis for comparing opportunity attractiveness across segments and locations. For existing operators, it supports refinement of service mixes, investment prioritization, and competitive response planning. For investors and advisory professionals, it delivers a structured synthesis of market size, growth trajectory, concentration dynamics, and structural risk factors that can inform diligence and valuation discussions.
Strategic Implications for 2026 Decision-Making
As organizations move into 2026 planning, several strategic priorities emerge from the market’s underlying structure. First, service differentiation will increasingly depend on execution quality and process reliability rather than price alone. As demand diversifies across corporate, retail, hospitality, healthcare, education, and residential channels, vendors that can tailor operating procedures, training, and dispatch logic to specific vertical expectations will capture stronger retention and pricing leverage.
Second, labor strategy will remain decisive. With wage floors established and employment growth projected to expand at a measured pace, operators must pursue productivity through standardized workflows, scheduling optimization, and targeted technology integration. Companies that treat labor not as a variable cost to be minimized but as a capability to be engineered will be better equipped to protect margins while meeting service-level expectations.
Third, regulatory and compliance awareness will shape both market access and operating model design. Safety standards, handling requirements, and labor classification frameworks influence training costs, contractor engagement models, and geographic feasibility. Forward-looking strategies should incorporate compliance mapping as a core planning input rather than a reactive operational concern.
Fourth, competitive positioning will increasingly reward clarity of scope and operational fit. The coexistence of platform marketplaces, branded franchise networks, rental-integrated providers, and specialized local operators creates a complex environment in which broad promises are less effective than well-scoped value propositions. Organizations that define where they compete, how they win, and which segments they intentionally serve will be better positioned to allocate capital and attention efficiently.
Final Perspective
The Worldwide Furniture Installation and Relocation Service Market is expanding along a measurable, structurally supported trajectory, but its real strategic value lies beneath the headline figures. Growth is unevenly distributed across service types, end-user segments, and geographies; competitive intensity is shaped by business model diversity; and operating economics are conditioned by labor costs, safety mandates, and regulatory frameworks. PW Consulting’s full market research consolidates these dimensions into a coherent intelligence asset, enabling decision-makers to move beyond surface-level sizing and engage the operational, competitive, and demand-side realities that will shape performance through 2032.
RTA (Ready-to-assemble) Furniture Market
For executives, investors, and service operators preparing for 2026, the complete report offers the segmentation depth, forecast discipline, competitive context, and operational insight required to translate market movement into actionable strategy. The full analysis, including detailed segmentation mapping, scenario frameworks, and competitive profiling, is available through the source publication and serves as a foundational reference for planning, investment evaluation, and market positioning across the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Furniture Installation and Relocation Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com